

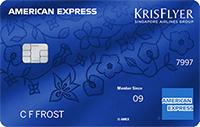
This is our review of the American Express Singapore Airlines KrisFlyer Credit Card issued in Singapore. It forms part of our series of credit card reviews, which are all summarised on our dedicated Credit Cards page.
Dollar amounts refer to SGD, and ‘miles’ refer to KrisFlyer miles, except where stated. This review was updated on 24th September 2026.
| KF Amex Blue Card | |||
 |
1.1 mpd local & FCY |
2 mpd SIA Group spend |
First year free |
| APPLY HERE | |||
| KF Amex Blue Card | ||
|
||
|
1.1 mpd local & FCY |
2 mpd SIA Group spend |
First year free |
| APPLY HERE | ||
Mainly Miles Says
The Amex KrisFlyer Credit Card earns 1.1 mpd on almost everything, which is now the lowest general spend rate of any miles card on the Singapore market, and there is no overseas bonus to offset it.
What it does have is a first year fee waiver that is easy to extend, direct fee-free crediting into your KrisFlyer account, and access to Amex Offers. That combination makes it a reasonable card to acquire for a sign-up bonus and then keep dormant, but rarely one to actually spend on.
| Pros | Cons |
|
|
The four-card range
American Express issues four Singapore Airlines co-brand credit cards in Singapore, and this review covers only the entry-level card, the plain “KrisFlyer Credit Card”, widely known as the KrisFlyer Blue.
| Amex Singapore Airlines Co-brand credit cards |
||
| Card | Who can hold one? |
Annual fee |
| Amex KrisFlyer Credit Card |
Open to all | S$179.85 (first year free) |
 Amex KrisFlyer Ascend Card |
Open to all | S$397.85 (no first year waiver) |
 Amex PPS Credit Card |
PPS Club members |
S$561.35 (first year free) |
 Amex Solitaire PPS Credit Card |
Solitaire PPS Club members* |
S$561.35 (first year free) |
* Principal Solitaire PPS Club members only. Supplementary members are not eligible.
The two PPS cards are invitation-gated by status, so for most readers the only choice is between the baseline Blue card we’re reviewing here, and the KrisFlyer Ascend card.
Eligibility
- Minimum Age (principal): 21
- Minimum Age (supplementary): 18
- Minimum Income: S$30,000
Amex’s product page no longer gives an income figure, only stating that applicants must meet the regulatory minimum and pass Amex’s own internal assessment.
In practice that means the MAS floor of S$30,000 per year. The regulation sets no separate figure for foreigners, but when Amex last published its requirements for this card it asked foreigners for S$60,000, so expect a higher internal bar if you’re not a Singapore citizen or PR.
Annual Fees & Interest Rates
- Annual Fee (principal): S$179.85 (first year free)
- Annual Fee (supplementary): S$54.50 (first two cards free in year one)
- Fee Waiver: generally granted on request
The annual fee sits at S$179.85, waived in the first membership year. Note that the first year waiver only applies if you are new to American Express and do not already hold another Singapore Airlines co-brand Amex card.
Supplementary cards cost S$54.50 each, with the first two waived in year one alongside the principal card.
Unlike UOB, which states that its KrisFlyer credit card is not eligible for a fee waiver, American Express makes no such claim. While there’s no published spend threshold for a waiver from year two onwards, reader reports consistently suggest a phone call is usually enough to achieve one.
That effectively turns this into a no-fee card indefinitely, which is partly the basis of the “acquire and park” case we make for it. However, if a waiver is refused from year two onwards there is no argument for paying S$179.85 to keep it, since there is no renewal bonus of any kind.
Other fees and interest rates for the card:
- EIR: 27.8%
- Interest-free period: 22 days (minimum)
- Minimum payment: 3% or S$50, whichever is greater
- Late payment fee: S$100 per month
- Cash advance fee: 5% handling fee, plus 26.9% p.a. from the withdrawal date
Sign-up bonus
There is a current sign-up bonus for the Amex KrisFlyer credit card, worth up to 16,000 bonus KrisFlyer miles, for approvals up to 31st January 2027.
The bonus is split into two components:
- 5,000 bonus miles on your first charge of any amount, for first-time applicants of any Singapore Airlines Amex co-brand card
- 11,000 bonus miles for S$2,000 of eligible spend within the first three months of approval, for those new to American Express
Add the base miles earned on that S$2,000 spend and the total looks like this:
| Sign-up bonus | |
| Miles | |
| First charge bonus | 5,000 |
| S$2,000 spend within 3 months | 11,000 |
| Base miles (S$2,000 @ 1.1 mpd) |
2,200 |
| Total | 18,200 |
That’s an effective 9.1 mpd on the qualifying spend, and around S$328 of value at a 1.8 cent per mile valuation, for a card that costs nothing in year one. On those terms it’s a perfectly sensible application.
The catches are all in the eligibility.
To qualify for the 11,000 miles you must not currently hold any basic or supplementary American Express consumer card, and must not have held one that was cancelled at any point in the preceding 24 months. That two-year lockout is considerably harsher than the 12-month version Amex used to run, and the inclusion of supplementary cards catches many people who wouldn’t necessarily think of themselves as Amex customers at all.
The 5,000 miles first-charge bonus is separately gated as a once-per-lifetime award across the entire Singapore Airlines co-brand family. If you have ever held the Ascend, a PPS card or this card before, you won’t see that bonus when you apply again.
Your spend must post within the three-month window rather than merely be transacted in it, and the bonus miles are awarded around 12 weeks after you hit the threshold. Amex can also claw the miles back if you close the account within six months of approval. Supplementary cardholder spend counts towards the S$2,000.
Sign-up bonuses on this card change several times a year and occasionally reach 22,900 miles for as little as S$1,000 of spend, so this current deal is a rather middling one.
Member invites
Every calendar year, cardholders receive three Member Invites to refer friends to American Express, worth 4,000 KrisFlyer miles each if the person you refer is new to Amex, so 12,000 miles a year in total.
It’s a nice perk and it costs nothing to use, but keep it in perspective. The same benefit on the KrisFlyer Ascend pays 15,000 miles per referral, currently boosted to 20,000 until 30th September 2026, so a maximum of 60,000 miles a year against this card’s 12,000.
Regular earn rate
The Amex KrisFlyer Credit Card has the weakest general spend earn rate of any miles card currently issued in Singapore.
- 1.1 mpd for local spend, uncapped
- 1.1 mpd for FCY spend, uncapped
That’s it. The same rate applies whether you’re buying groceries in Singapore or settling a hotel bill in Tokyo, and the only bonus categories are SIA Group and Grab spend, which we cover below.
Here’s how that stacks up against the other general spend cards in Singapore at a comparable income level.
Earn rates (general spend cards)
(Best to worst, September 2026)
| Card | Local Spend | FCY Spend |
 BOC EM |
1.4 mpd | 2.8 mpd |
 UOB PRVI Miles |
1.4 mpd | 2.4 mpd |
 DBS Altitude |
1.3 mpd | 2.2 mpd |
 OCBC 90oN |
1.3 mpd | 2.1 mpd |
 HSBC T1 |
1.2 mpd | 2.4 mpd |
 Citi PM |
1.2 mpd | 2.2 mpd |
 SC Journey |
1.2 mpd | 2 mpd |
| KF Ascend |
1.2 mpd | 1.2 mpd |
 KF UOB |
1.2 mpd | 1.2 mpd |
| KF Blue |
1.1 mpd | 1.1 mpd |
Last on both counts, and the only card on the list below 1.2 mpd.
If you spend S$1,500 a month in SGD and S$500 a month in FCY on this card over a year, you’ll finish up with 26,400 KrisFlyer miles.
The same spend on the BOC Elite Miles card earns 42,000 KrisFlyer miles.
That gap of 15,600 miles a year is worth around S$280, which is more than an annual fee you probably aren’t paying anyway for the BOC card – so it’s significant value you’re leaving behind for no reason.
SIA Group earn rate
As a co-brand card, this one does earn an uncapped enhanced rate of 2 mpd on Singapore Airlines Group spend, incorporating:
- Singapore Airlines flight bookings made through singaporeair.com, the SingaporeAir app, or by phone
- Scoot bookings made through flyscoot.com or the Scoot app
- KrisShop purchases, both onboard and at krisshop.com
- Pelago bookings made at pelago.com or through the Pelago app
There’s no cap and no minimum spend, and the rate applies to award ticket taxes and surcharges as well as commercial fares, so paying the fees on a redemption booking earns at 2 mpd on the taxes.
Two things to be aware of, and the first has caught readers out before. Flights must originate in Singapore and be purchased in Singapore dollars. Readers have also reported Singapore-originating bookings, paid in Singapore dollars, being refused the bonus simply because they were made on singaporeair.com from overseas. Where you can, book while you’re in Singapore.
Second, KrisShop and Pelago purchases made through the Kris+ app do not qualify for the 2 mpd rate. You need to transact directly with those platforms, and yes that means the Kris+ earn rate with this card is 1.1 mpd, not 2 mpd, despite Kris+ being what most would consider “SIA Group”.
Uncapped 2 mpd is not nothing, but it is not competitive either. The KrisFlyer UOB credit card pays an uncapped 3 mpd on the same set of merchants, plus on all Kris+ spend, and several bonus category cards will pay 4 mpd on airline tickets up to a monthly cap, like the DBS WWMC, HSBC Revolution and Maybank XL Rewards.

(Photo: Lucas Wunderlich / Shutterstock)
Grab earn rate
Grab Singapore transactions with this card earn 2 mpd on the first S$200 charged in each calendar month, which covers Grab rides, GrabFood, GrabMart and Grab Express.

This is the base 1.1 mpd plus a 0.9 mpd bonus, with the bonus element awarded in blocks of S$10 based on cumulative monthly Grab spend, credited at the end of each calendar month. Spend beyond S$200 reverts to the standard 1.1 mpd.
GrabPay top-ups do not count.
This used to be one of the card’s better features at 3.1 mpd, before it was cut to 2 mpd on 1st November 2024. At the current rate, with a S$200 monthly cap, the absolute maximum bonus on offer is 2,160 miles a year on top of what you’d earn anyway with this card, which isn’t much.
What happened to the June and December bonus?
If you’re arriving here from an older article or an out of date comparison, you may be expecting a 2 mpd overseas earn rate during June and December. That feature is gone.
American Express withdrew it on 1st November 2024, as part of a wider refresh of all four Singapore Airlines co-brand cards, and foreign currency spend has earned the flat 1.1 mpd year-round with this card ever since.
We won’t pretend to mourn it.
A bonus rate available for two months out of twelve was always an awkward thing to plan spending around, and even at 2 mpd it was beaten by many alternatives. However, its removal does mean this card now has no overseas earning proposition whatsoever, which you’ll see in the cost per mile calculation below.
Eligible transactions
Alongside the usual exclusions for cash advances, fees, interest charges, balance transfers and instalment plans, the following earn no miles:
- Bill payments and all transactions via SingPost, including SAM kiosks, the mobile app and the online portal
- Payments to insurance companies, except insurance bought through Amex’s own authorised channels
- Payments at Singapore Petroleum Company (SPC) service stations
- Payments for public transit in Singapore, including trains and buses and anything bearing the merchant description “BUS/MRT”
- Stored value card purchases, loads and top-ups, and topping up digital wallets including GrabPay and ShopeePay, with effect from 30th September 2025
- Payments to utilities merchants
- Payments to public and restructured hospitals, polyclinics and other public healthcare institutions
- Education and other non-profit transactions, including charitable donations
- Any merchant excluded by American Express at its discretion and notified to you
When we reviewed this card in 2020, its exclusion list was short enough that Amex acceptance was the bigger obstacle to earning. That’s no longer the case. SimplyGo journeys, utilities, public hospitals, education, charitable donations and digital wallet top-ups have all been added since.
Anything not on the list still earns, including bills paid through CardUp and ipaymy, though Amex sets its own limits on which CardUp payments it allows. At 1.1 mpd, standard Amex fees of 2.9% at CardUp and 2.4% at ipaymy work out to 2.56 and 2.13 cents per mile respectively, so it’s rarely worth doing.
The current spend exclusions can be found at go.amex/sgexclusions.
Are KrisFlyer miles credited directly?
Yes. This is a Singapore Airlines co-brand card, so miles earned are credited straight into the KrisFlyer account linked to your card, on a monthly basis, and reflected on your monthly statement.

You need a valid KrisFlyer membership in your own name linked to the card account before you start spending. If the details you’ve supplied are wrong or incomplete, the miles simply won’t credit.
If your card account is cancelled for any reason, you stop earning from that point, but miles already earned as of the cancellation date are still credited to your KrisFlyer account.
That’s quite unlike the KrisFlyer UOB credit card, whose terms allow UOB to forfeit miles that have been earned but not yet credited if you close the account first – a clause we’ve always been critical of, since it effectively holds you to ransom at renewal.
The flip side of direct crediting is that each month’s miles start their three-year KrisFlyer expiry the moment they land. Bank points can buy you time – DBS Points on the Altitude card never expire, for example, so the KrisFlyer clock only starts when you choose to convert.
What is the transfer cost?
There isn’t one. Because miles are credited automatically each month rather than converted on request, there is no transfer fee, and no minimum transfer block.
That’s a nice advantage over the non-co-brand cards, where conversion fees of S$25 to S$30 per transfer are common, and where you often need to transfer at least 10,000 miles at a time, in blocks of 10,000 thereafter.
When do miles credit?
Miles credit in one monthly batch, covering transactions posted to your account within each statement period, and typically appear in your KrisFlyer account around the close of that statement cycle.
Intermediate transfers aren’t supported, so miles from a large purchase can’t be pulled across early for an urgent redemption – you could be waiting over a month.
Also be aware that American Express works on posting date, not transaction date. A transaction can take a couple of days to post, so anything charged right at the end of your statement period may fall into the next one, and that means waiting longer than you might have expected for the associated miles.
Can I transfer miles into other loyalty schemes?
No. KrisFlyer is the only partner, and there is no mechanism to direct your earnings anywhere else. That’s inherent to a co-brand product, as you might expect.
Most Singapore miles cards give you a choice, of course.
Citi’s ThankYou Points transfer to ten frequent flyer programmes plus IHG on the hotel side. Almost every bank other than BOC offers Asia Miles as an alternative to KrisFlyer, while four banks offer at least one route into the Avios ecosystem, both of which unlock the Oneworld network for redemptions.


There is one incidental upside to the co-brand structure.
When American Express devalued its Membership Rewards transfer ratios in January 2026, pushing up the points cost of miles across almost every airline partner, the Singapore Airlines co-brand cards were unaffected, because they earn KrisFlyer miles directly rather than the transferable Membership Rewards currency.
So while you give up flexibility with a co-brand card, you also avoid exposure to that kind of change.
Miles rounding
American Express calculates miles on the exact transaction amount, then rounds the result to the nearest whole mile – fractions of 0.50 or more round up, anything below rounds down.
- S$13.00 x 1.1 = 14.3 miles, rounded down to 14 miles
- S$15.00 x 1.1 = 16.5 miles, rounded up to 17 miles
This is much more generous than it first appears, and it’s one of the few places where this card beats its competition. There’s no rounding of the spend down to a whole dollar or a block, which is what most issuers do.
The contrast with UOB is stark, with the latter awarding miles per whole S$5 block, so a S$9.99 transaction is treated as S$5. Here’s how it looks on a like-for-like basis:
| KrisFlyer miles awarded | ||
| SGD Charge |
KF Blue (1.1 mpd) |
 KF UOB (1.2 mpd) |
| S$4.99 | 5 miles | 0 miles |
| S$9.99 | 11 miles | 6 miles |
| S$15.00 | 17 miles | 18 miles |
| S$19.99 | 22 miles | 18 miles |
For a wallet full of small transactions – a coffee here, a bowl of noodles there – the nominally worse card can actually come out ahead. It’s a narrow consolation given everything above, but it can sometimes work in your favour.
↥ Minimum spend to earn miles
Because of that rounding policy, the minimum charge needed to earn a mile is very low:
- S$0.46 at the 1.1 mpd rate (0.506 miles, rounds up to 1)
- S$0.25 at the 2 mpd rate (0.5 miles, rounds up to 1)
For comparison, the KrisFlyer UOB credit card needs S$5.00, the DBS Altitude S$1.54, and the Citi PremierMiles S$1.00.
FCY fee / cpm overseas
The card charges a foreign currency transaction fee of 3.25%, applied as a conversion commission on top of the American Express Exchange Rate. That fee was 2.95% until 2020, and 2.5% before that.
Paired with a 1.1 mpd earn rate and no overseas bonus of any kind, the result is the worst cost per mile of any card we track.
| Cost per mile on overseas transactions (general spend cards) (Best to worst, September 2026) |
|||
| Card | Fee | Mpd | Cost per mile |
| BOC EM |
3% | 2.8 | 1.14¢ |
 Maybank HVS |
3.25% | 2.8* | 1.22¢* |
 SCVI |
3.5% | 3.0** | 1.22¢** |
| HSBC T1 |
3.25% | 2.4 | 1.43¢ |
| UOB PRVI Miles |
3.25% | 2.4 | 1.43¢ |
| Citi PM |
3.25% | 2.2 | 1.56¢ |
| DBS Altitude |
3.25% | 2.2 | 1.56¢ |
 OCBC Voyage |
3.25% | 2.2 | 1.56¢ |
 OCBC 90oN |
3.25% | 2.1 | 1.63¢ |
 HSBC VI |
3.25% | 2.0 | 1.71¢ |
| SC Journey |
3.5% | 2.0 | 1.83¢ |
| KF UOB |
3.25% | 1.2 | 2.86¢ |
| KF Ascend |
3.25% | 1.2 | 2.86¢ |
| KF Blue |
3.25% | 1.1 | 3.12¢ |
* Maybank Horizon Visa Signature: minimum S$800 spend per calendar month required.
** Standard Chartered Visa Infinite: minimum S$2,000 spend per statement period required.
Cost per mile accounts for an additional 0.30% ‘spread’ over money changer currency rates, and reflects miles earned on the billed amount inclusive of the fee. This doesn’t apply to all banks and all foreign currencies, so it’s a worst-case scenario.
At 3.12 cents per mile, you are paying well above what we consider a KrisFlyer mile to be worth, before you’ve even flown anywhere. Use almost any other card!
Don’t expect the SIA Group rate to rescue you either. The 2 mpd bonus only applies to purchases made in Singapore dollars, so a Singapore Airlines, Scoot, KrisShop or Pelago charge billed in foreign currency drops back to 1.1 mpd, the same lousy 3.12 cents per mile cost.
S$150 Singapore Airlines cashback
The card’s headline non-miles benefit is S$150 cashback towards a Singapore Airlines booking, earned by charging S$12,000 or more to the card within the qualifying period, currently 1st July 2026 to 30th June 2027.
The conditions are more specific, though:
- The redeeming booking must be a Singapore Airlines flight originating from Singapore, purchased in Singapore dollars, through singaporeair.com or the SingaporeAir app
- It must be a single transaction of at least S$800
- It must be completed within 12 months of the date you hit the S$12,000 spend
- Bookings made via Pay Small are excluded
- One award per cardholder per qualifying period
- The credit appears on your statement around 90 days after the qualifying booking, and can be reversed if that booking is cancelled or refunded
Taken at face value, S$150 back on S$12,000 of spend is a 1.25% return. Framed in miles, and valuing the cashback at our 1.8 cent benchmark, it’s worth about 8,300 miles, which spread across S$12,000 of spend adds roughly 0.69 mpd.
That’s the most useful way to look at it. It lifts your effective earn rate on the first S$12,000 of annual spend from 1.1 mpd to around 1.79 mpd, which finally puts this card in the same territory as its rivals, but only up to that threshold, and only if you were always going to buy an S$800+ Singapore Airlines ticket anyway.
If you weren’t, it’s worth nothing at all, and if you were, you could probably have earned those miles more cheaply, and with fewer conditions, simply by using a better card in the first place.
Amex Offers
The most compelling reason to hold this card has nothing to do with KrisFlyer miles.
Amex Offers are targeted promotions pushed to cardholders through the Amex app and online account, and they can be substantially valuable – statement credits on hotel bookings with Hilton, IHG, Marriott, Shangri-La and Four Seasons, savings on airline tickets, bonus miles promotions with particular merchants, and small everyday rebates.
Offers are sometimes targeted rather than universal, so what you see may not match what your neighbour sees, and each has to be saved to your card before you spend. Over a year, you can sometimes extract several hundred dollars of value from these promotions.
None of this is exclusive to this card – other Amex cards also receive offers. The difference is cost, because this card is free in year one and the fee is routinely waived after that, which makes it the cheapest way to stay on Amex’s Offers list.
Pay Small
American Express offers Pay Small, its 0% interest instalment facility, on Singapore Airlines ticket purchases at singaporeair.com.

The following conditions apply:
- Six-month instalment option only
- Charge of S$250 or more
- Purchase must be made at singaporeair.com
- Travel must originate in Singapore, and payment must be in Singapore dollars
- You must select the Pay Small option at checkout
- Your card account must be paid in full each month
Tickets bought through Pay Small earn no KrisFlyer miles at all, a change since our 2020 review, when they still earned 0.5 mpd. Amex’s current Pay Small terms exclude every rewards currency from instalment charges, save for the occasional campaign that says otherwise.
The trade-off is just that. The same booking would normally earn 2 mpd, so you’re surrendering every mile for the cash flow benefit. On a S$5,000 Business Class fare that’s no miles instead of 10,000, a loss worth around S$180 to most readers.
Pay Small bookings also don’t count for the S$150 Singapore Airlines cashback, outlined above.
For most readers, this isn’t a benefit so much as a facility to be aware of, and avoid.
No lounge access
There is no complimentary airport lounge access with this card, in any form. No Priority Pass, no Dragon Pass, no SilverKris or KrisFlyer Gold entry.
Given the Singapore Airlines branding, that’s the benefit readers might assume is included. Most are disappointed to find it simply isn’t, not even a pair of passes to the KrisFlyer Gold Lounge each year when flying SIA.

(Photo: MainlyMiles)
Several cards at a comparable fee do include lounge access:
- Citi PremierMiles: 2 Priority Pass visits per year
- DBS Altitude Visa: 2 Priority Pass visits per year
- Standard Chartered Journey: 2 Priority Pass visits per year
- HSBC TravelOne: 4 Dragon Pass visits per year
- UOB PRVI Miles: 4 Priority Pass visits per year
See our guide to cards with free airport lounge access for the full list of alternatives.
Other benefits
- Travel insurance: Charge your full return fare to the card and you’ll be covered by a Chubb policy of up to S$350,000 for accidental death or total disablement on public transport outside Singapore. There’s also modest travel inconvenience cover of S$200 per person for flight delays, missed connections and baggage delays. That’s half the S$400 figures usually quoted, which are the per family maximums.
There is no cover for medical expenses or emergency evacuation, so treat this as a top-up to a proper travel insurance policy, never a substitute for one. - Hertz: Cardholders get Hertz Gold Plus Rewards membership, with up to 10% off rentals worldwide, a one car class upgrade subject to availability, and a free additional driver. It’s a nice extra, though Gold Plus Rewards is free to join directly anyway, and the same benefits come with the Ascend and many other cards.
Merchant acceptance
One factor to consider is that American Express is not accepted as widely in Singapore as Visa and Mastercard.

That said, acceptance has improved considerably over the last decade, and you’ll rarely have trouble at larger retailers, restaurant groups, hotels or online. But smaller independent merchants and a good number of QR-code payment setups remain patchy or won’t take Amex at all.
If you’re planning to use this as your primary everyday card (why?), the acceptance gap could become a daily nuisance on top of an already poor earn rate.
How it compares to the KrisFlyer Ascend
The obvious question for anyone considering this card is whether to just pay up for its sibling instead.
| Amex KrisFlyer Credit Card vs. KrisFlyer Ascend Card |
||
| Amex KF Credit Card |
Amex KF Ascend Card |
|
| Annual fee | S$179.85 (first year free) |
S$397.85 (no first year waiver) |
| Supplementary fee | S$54.50 (first 2 free in yr 1) |
S$81.75 (first 2 free in yr 1) |
| General spend | 1.1 mpd | 1.2 mpd |
| FCY spend | 1.1 mpd | 1.2 mpd |
| SIA Group spend | 2 mpd | 2 mpd |
| Grab | 2 mpd (S$200/mth) |
2 mpd (S$200/mth) |
| Renewal bonus | None | 10,000 miles redemption voucher |
| FCY spend bonus | None | 18,000 miles redemption voucher at S$10,000 FCY spend |
| KF Elite Gold fast track | No | Yes (S$15k spend) |
| Hilton free night | No | One per year (Asia Pacific) |
| Hilton Honors status | No | Silver |
| Travel accident cover | S$350,000 | Up to S$1 million |
| Member Invites | 4,000 miles each (12,000/yr) |
15,000 miles each (45,000/yr) |
| Lounge access | None | None |
| S$150 SIA cashback | Yes | No |
Neither card earns well. The Ascend’s advantage is 0.1 mpd on general spend, which on S$30,000 of annual spend is 3,000 extra miles, worth around S$50 – nowhere near the S$218 fee difference on its own.
The Ascend’s case rests entirely on its benefits package – the annual Hilton night, the two miles redemption vouchers, and the KrisFlyer Elite Gold fast track. If you’ll definitely use the Hilton night and can hit the Elite Gold spend criteria, the sums can work.
If you won’t, they very clearly don’t, and the blue card is the better choice by default because it costs nothing and still gives you Amex Offers.
Terms and conditions
Here are links to the full terms and conditions applicable to this card.
- Card Member Agreement and Benefits TnCs
- Sign-Up Promotion TnCs
- Travel Insurance Policy Wording
- Excluded Transactions
Our Summary
The Amex KrisFlyer Credit Card is not a card to spend with.
At 1.1 mpd locally and overseas, with a 3.25% foreign currency fee producing a cost per mile of 3.12 cents outside Singapore, it sits at the bottom of practically every table we produce, and the loss of the June and December overseas bonus in November 2024 cemented that.
It is, however, a card worth acquiring. The sign-up bonus is regularly among the most generous on the market relative to the spend required, the first year costs nothing, and the fee is reliably waived thereafter. That makes it close to free to hold indefinitely.
What you get for that is access to Amex Offers, which can be worth several hundred dollars a year to anyone who checks them, an uncapped 2 mpd on Singapore Airlines Group spend for when your bonus category caps run dry, and the S$150 Singapore Airlines cashback if you’re spending S$12,000 a year and buying an S$800+ SIA ticket anyway.
The generous rounding on small transactions also works in its favour for this type of spend.
Set against that, there’s no lounge access, a single transfer partner, an exclusion list that has grown noticeably over the past two years, patchier merchant acceptance than a Visa or Mastercard, travel insurance with no medical cover at all, and a three-year KrisFlyer expiry clock that starts running almost immediately.
Apply for the bonus, take the free first year, use it for Amex Offers, and spend on something else.
| Our Rating | ||||||||||||||||||||
| 2 / 5 among general spend cards |
||||||||||||||||||||
|
Amex KrisFlyer Credit Card |
||||||||||||||||||||
How we rate credit cards
|
||||||||||||||||||||
(Cover Photo: Shutterstock)