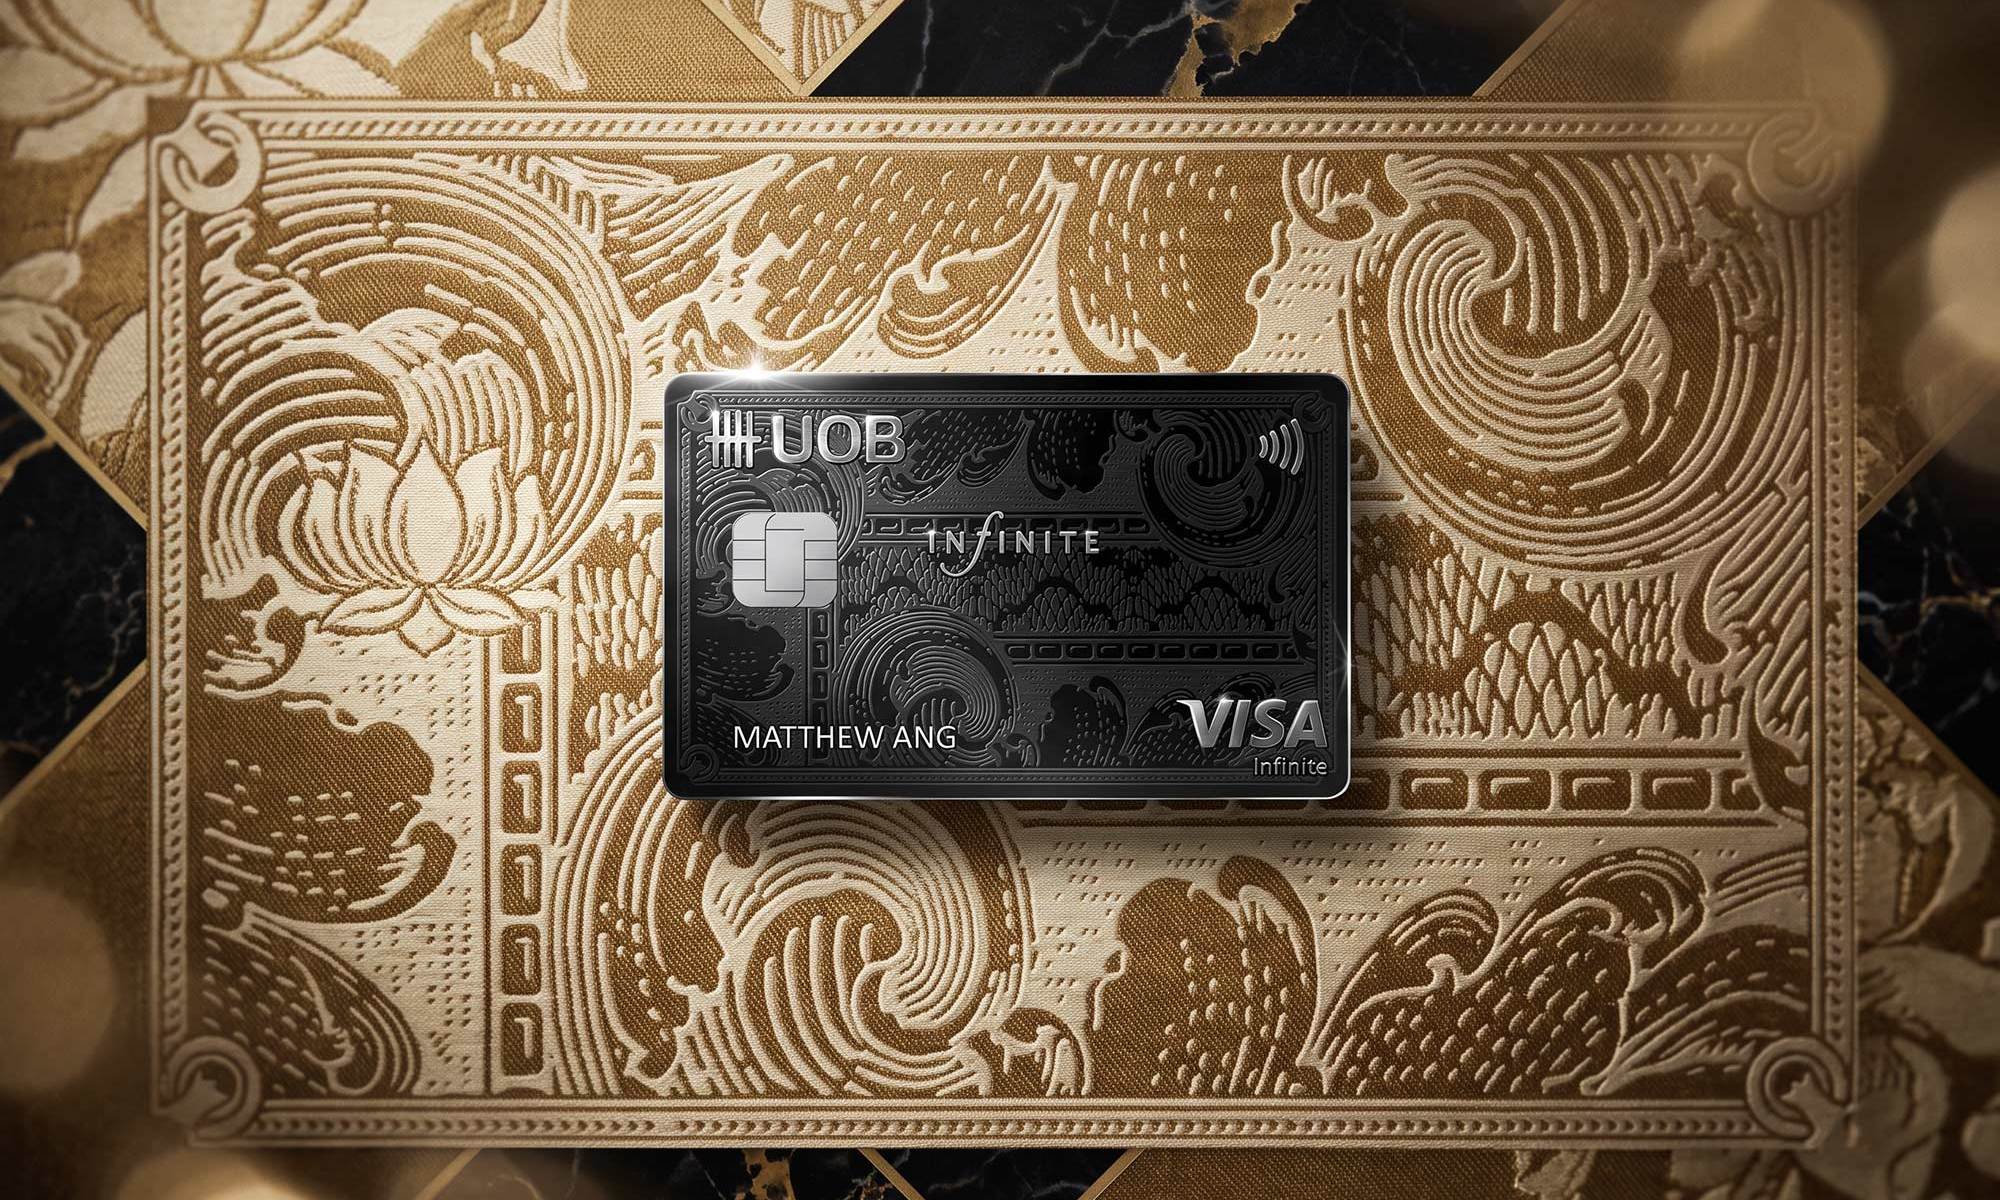

Here’s our review of the UOB Visa Infinite Metal Card issued in Singapore. It forms part of our series of credit card reviews, which are all summarised on our dedicated Credit Cards page.
Dollar amounts refer to SGD, and ‘miles’ refer to KrisFlyer miles, except where stated. This review was updated on 10th November 2026.
| UOB Visa Infinite Metal | |||
 |
25,000 miles each year |
12 annual lounge visits |
Free miles transfers |
| APPLY HERE | |||
| UOB Visa Infinite Metal | ||
|
||
|
25,000 miles each year |
12 annual lounge visits |
Free miles transfers |
| APPLY HERE | ||
Mainly Miles Says
UOB’s Visa Infinite Metal Card earns 1.4 mpd locally and 2.4 mpd overseas, gives you 25,000 miles every time you pay the S$654 annual fee, and waives the conversion fee on UNI$ from all your UOB cards. But with unlimited lounge access cut to 12 visits from June 2026, are the perks enough to justify the cost?
For most readers, the answer depends on how it stacks up against UOB’s own PRVI Miles card, which earns at the same rates (or higher) for 40% of the fee.
| Pros | Cons |
|
|
Eligibility
- Minimum Age: 21
- Minimum Income: S$120,000/yr
The UOB Visa Infinite Metal Card is in the S$120,000 income bracket, alongside cards like the Citi Prestige, DBS Vantage and Standard Chartered Visa Infinite. The same threshold applies to Singaporeans, PRs and foreigners.
Annual Fees & Interest Rates
- Annual Fee (principal): S$654 (S$600 + GST)
- Annual Fee (supplementary): first card free for life, then S$293.38 each
- Fee waiver: none
The annual fee for the UOB Visa Infinite Metal Card is S$654, charged from day one and reflected on your first statement. Unlike many miles cards, there’s no free first year, and UOB’s terms are explicit that the fee can’t be waived at any point, so there’s no point calling up to ask.
In return, you’ll receive 25,000 miles every time the fee is paid, including the first year.
Your first supplementary card is free for life, with any further supplementary cards charged at S$293.38 a year each.
Other fees and interest rates for the card:
- Interest rate: 27.8% p.a.
- Minimum payment: 3% or S$50, whichever is greater
- Late payment fee: S$100
- Cash advance fee: 8% (minimum S$15)
- Overlimit fee: S$40
25,000 miles every year
Each time you pay the S$654 annual fee, UOB credits UNI$12,500, worth 25,000 miles. In the first year this is labelled as a ‘Welcome Gift’, and in subsequent years as an ‘Annual Bonus’, but the amount is the same.
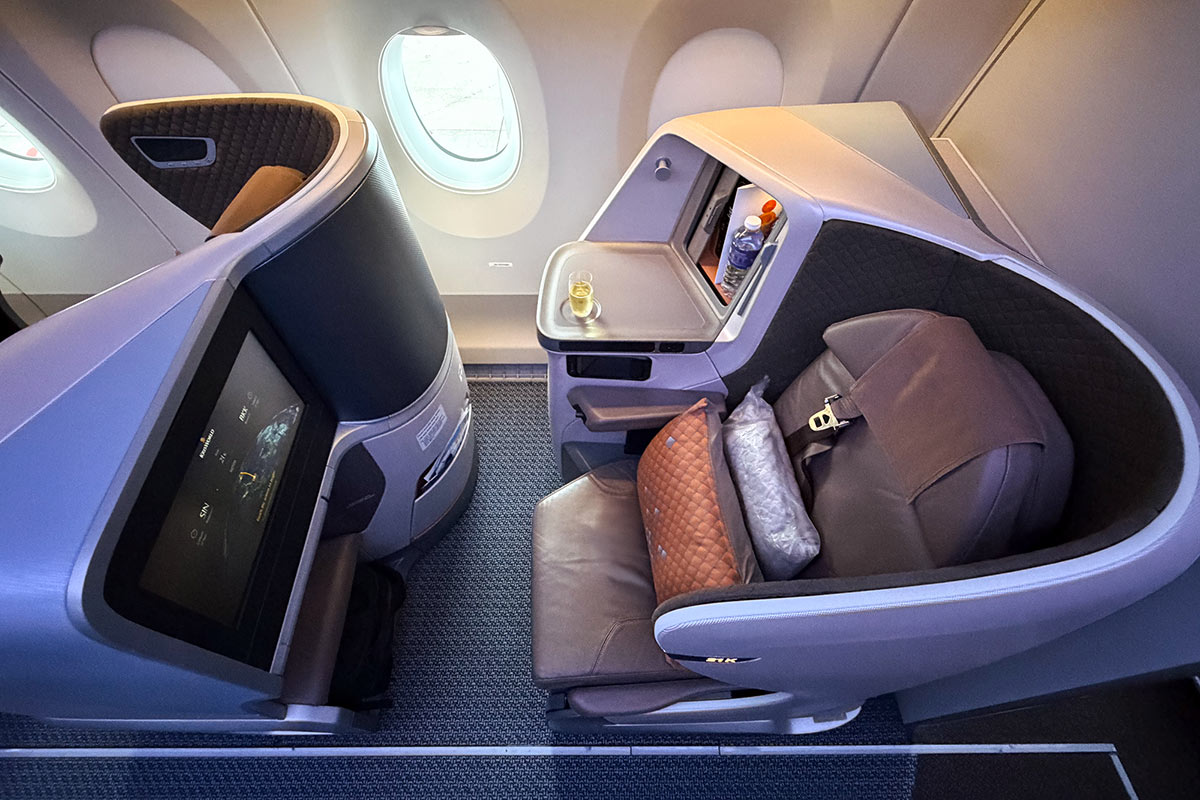
(Photo: MainlyMiles)
The UNI$ arrive roughly two months after the fee posts to your account.
On its own, that’s equivalent to ‘buying’ miles at 2.62 cents each (S$654 ÷ 25,000), well above the 1.8 cents we would typically value a KrisFlyer mile at.
The other way to look at it is if you value those 25,000 miles at 1.8 cents each (S$450), the card’s lounge access, free transfers, insurance and other perks are effectively costing you around S$204 a year.
Loyalty bonus: 15,000 miles for S$100,000 spend
If you charge at least S$100,000 in eligible spend to the card during a membership year, and then renew and pay the next annual fee, UOB will credit a further UNI$7,500 (15,000 miles). That’s 40,000 miles in total for renewing, on top of the miles earned from the spend itself.
A few points to note:
- Spend window: The 12-month period starts on the 1st of the month your annual fee posts. For example, if your fee posts in November 2026, you’ll need S$100,000 between 1st November 2026 and 31st October 2027.
- Timing: The bonus is credited two months after your next annual fee posts, so in that same example, in January 2028.
- Supplementary spend counts towards the S$100,000 target.
- Posting date is what matters, not the transaction date.
At exactly S$100,000, the bonus is worth an extra 0.15 mpd, lifting the effective local rate to 1.55 mpd and the overseas rate to 2.55 mpd. To unlock it, you’d need to average more than S$8,300 a month on a card earning 1.4 mpd locally, when much of that spend could earn more on 4 mpd cards, at least up to their monthly caps.
The most realistic route is large, regular bills that most miles cards won’t reward, like school or university fees (which do earn miles on this card), or rent and tax payments made via CardUp.
Sign-up bonus
The UOB Visa Infinite Metal Card currently has a sign-up bonus of up to 60,000 miles, for cards applied for and approved by 31st December 2026.
That’s made up of the regular 25,000 miles for paying the first year’s fee, plus additional bonus miles if you spend S$4,000 within 30 days of your card approval date.

| UOB VI Metal sign-up bonus (Approved by 31st December 2026) |
||
| New to UOB credit cards |
Existing UOB cardholder |
|
| Pay S$654 annual fee |
25,000 miles | 25,000 miles |
| Spend S$4,000 in 30 days |
35,000 miles | 15,000 miles |
| Total bonus (cost per mile) |
60,000 miles (1.09¢) |
40,000 miles (1.64¢) |
To count as new to UOB, you must not hold a principal UOB credit card when your application is approved, and must not have cancelled one in the 12 months before your approval date. Holding only a supplementary UOB card doesn’t stop you qualifying.
The spend window is counted by posting date, so don’t leave the final transactions until day 29 or 30. Supplementary card spend counts towards the S$4,000, and the extra bonus miles arrive two months after your annual fee posts.
For new-to-UOB applicants, buying 60,000 miles for S$654 (1.09 cents each) is a decent deal, though well short of the 80,000 miles UOB offered in 2024, a deal it kept running until mid-2025 at just 0.82 cents per mile.
Full terms and conditions for the current offer can be found here, and our dedicated article has all the details.
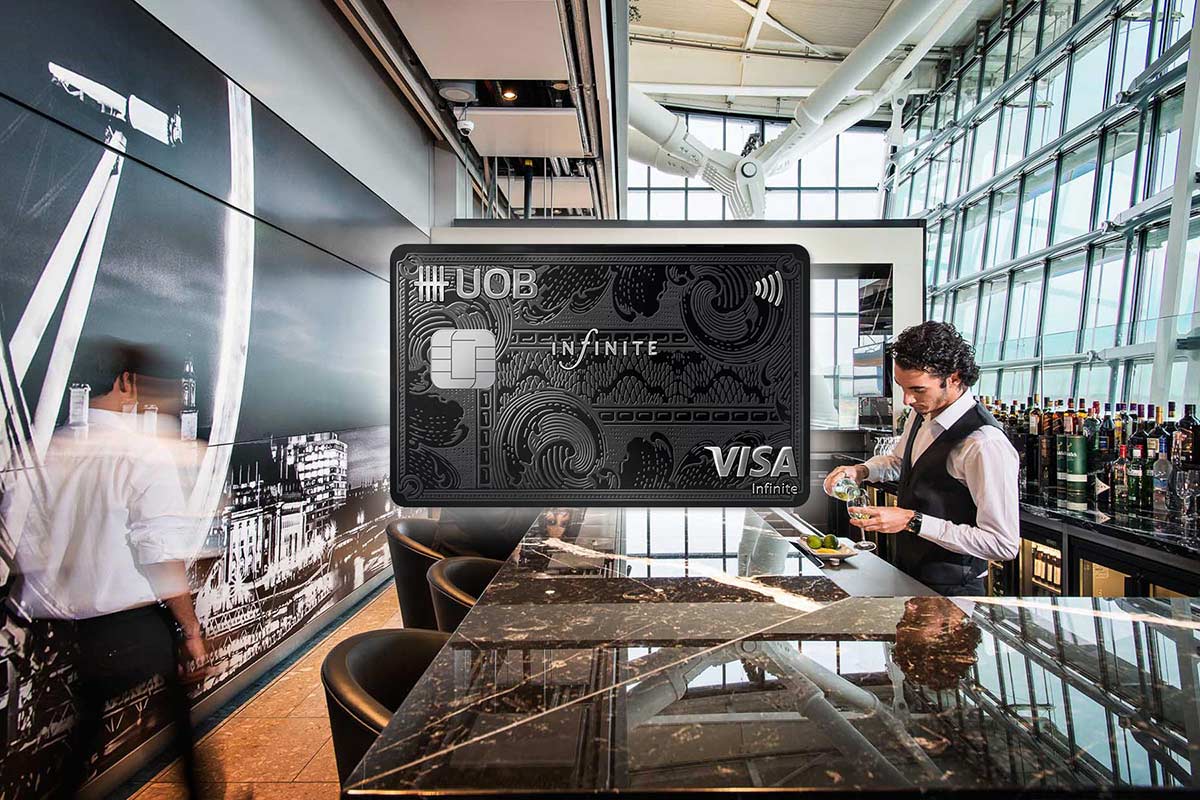

Regular earn rates
The UOB Visa Infinite Metal Card earns:
- 1.4 mpd on local spend in SGD (UNI$3.5 per S$5)
- 2.4 mpd on FCY spend processed overseas (UNI$6 per S$5)
There’s no minimum monthly spend and no cap on either rate, unlike some other cards in this income bracket.
Here’s how that compares with other S$120k income category cards in Singapore.
| Earn rates S$120k income cards (Best to worst, November 2026) |
||
| Card | Local Spend | FCY Spend |
 SCVI |
1.4 mpd* | 3 mpd* |
 UOB VI Metal |
1.4 mpd | 2.4 mpd |
 DBS Vantage |
1.4 mpd | 2.2 mpd |
 OCBC Voyage |
1.3 mpd | 2.2 mpd |
 Citi Prestige |
1.3 mpd | 2 mpd |
 Maybank VI |
1.2 mpd | 3.2 mpd^ |
 HSBC VI |
1 mpd | 2 mpd |
* Subject to a minimum spend of S$2,000 (any currency) in the same statement cycle, otherwise 1 mpd
^ Subject to S$4,000+ spend per calendar month, otherwise 2 mpd
On headline rates, the UOB VI Metal is near the top of this group. It’s the only one earning 1.4 mpd or more locally and 2.4 mpd or more overseas with no minimum spend attached.
If you spend S$3,000 a month in SGD and S$1,000 a month in FCY, you’ll earn 79,200 miles a year from spend, plus the 25,000 miles for paying the annual fee.
The problem is that UOB’s much cheaper PRVI Miles cards earn exactly the same 1.4 mpd and 2.4 mpd, and even earn 3 mpd on spend in Indonesian Rupiah, Malaysian Ringgit, Thai Baht and Vietnamese Dong.
Overseas, but processed in Singapore
As with other UOB cards, the 2.4 mpd rate depends on where your payment is processed, not just the currency you pay in.
- A foreign currency online purchase routed through a payment gateway in Singapore earns just 1.4 mpd (the local rate)
- Any overseas purchase charged in SGD also earns 1.4 mpd (the local rate)
The second point means you should always decline dynamic currency conversion when travelling. You’ll get a worse exchange rate and lose a full 1 mpd in the process.
For online merchants you’ll use repeatedly, make a small first purchase and check whether it earned UNI$6 or UNI$3.5 per S$5 once it posts.
Eligible transactions
UNI$ aren’t awarded for the usual exclusions, such as cash advances, balance transfers, instalment plans, fees and interest charges.
Beyond those, these are the main categories that don’t earn UNI$ on this card:
- Top-ups and wallets: GrabPay, YouTrip, EZ-Link, FlashPay, NETS VCashCard and other prepaid or mobile wallet loads, plus Amaze
- Bill payment services: AXS, SingPost SAM, ipaymy, RazerPay and Smoove Pay
- Insurance and utilities: insurance premiums of all kinds, and utility bills (MCC 4900)
- Government: tax payments, fines, court costs and other government services
- Healthcare: hospitals (MCC 8062)
- Property and parking: rent through real estate agents, property management fees, and car parks
- Financial: wire transfers, brokerages, forex and crypto platforms, and other quasi-cash transactions
- Organisations: charities, religious, political and membership organisations, and professional services not classified elsewhere
- Other: gambling, cigar shops, catalogue merchants (MCC 5965), nondurable goods (MCC 5199), and SPC and Shell service stations
The full list is in section 1.5 of the card’s terms and conditions.
Notably, education isn’t on the exclusion list, so school, university and tuition fees paid directly by card earn the full 1.4 mpd. That’s unusual, since most miles cards in Singapore (including the PRVI Miles) exclude education spend, and it could make the S$100,000 loyalty bonus more easily achievable for some cardholders.
CardUp payments also earn UNI$, though ipaymy transactions don’t.
SimplyGo
Bus and MRT fares paid by tapping the card earn the standard 1.4 mpd. UOB totals your SimplyGo fares across each calendar month before calculating UNI$, which are then credited by the 7th of the following month.
That means individual fares well below S$5 still earn miles, and relatively little is lost to rounding if you regularly charge several fares to the card across a month.
Posting date, not transaction date
UOB counts your spend by the date it posts to your account, typically one to three days after the transaction itself.
That matters for the 30-day sign-up bonus window and the S$100,000 loyalty bonus year, so leave yourself a few days’ margin at the end of either.
When do UNI$ credit?
UNI$ are credited as each transaction posts, so you won’t need to wait for your statement.
The exceptions are the annual fee miles, sign-up and loyalty bonuses (all two months after the relevant annual fee posts), SimplyGo fares (monthly), and UOB Travel Concierge bonus UNI$ (within three months).
Do UNI$ expire?
Yes. UNI$ expire two years after the end of the calendar quarter in which you earn them, so UNI$ earned in November 2026, for example, would expire on 31st December 2028.
That’s disappointing for a premium card, especially when you consider that the Citi Prestige’s more flexible points (11 transfer partners) never expire at all.
The free transfers on this card (see below) do soften the blow though. There’s no fee penalty for moving UNI$ across to KrisFlyer as soon as you reach each 10,000-mile block, where they’ll then be valid for another three years.
UNI$ pool between cards
UNI$ from all your UOB cards are combined into one balance. If you hold the VI Metal alongside a 4 mpd card like the UOB Preferred Visa or a UOB Lady’s Card, you can transfer everything together.
You can also cancel a UOB card without losing your UNI$, as long as you still hold another UOB card that earns them. If the VI Metal is your last one, transfer your UNI$ out first, because they’re forfeited when the account closes.
Which loyalty schemes can I transfer into?
UNI$ transfer to three frequent flyer programmes, though only two are worth considering.
| Frequent Flyer Programme |
Transfer Blocks (UNI$ Miles) |
|
 |
Singapore Airlines KrisFlyer |
5,000 10,000 |
 |
Cathay Pacific Asia Miles |
5,000 10,000 |
 |
AirAsia Rewards |
2,500 4,500 |
AirAsia points convert at a worse ratio and are worth only a fraction of a KrisFlyer mile or Asia Mile, so we’d ignore that option entirely.
Only two useful partners is disappointing for a S$654 card, but KrisFlyer and Asia Miles do at least cover Star Alliance and oneworld redemptions, which will be enough for many of our readers.
Free transfers to miles
This is one of the most useful benefits of the card.
UOB normally charges S$27 per UNI$ conversion, a fee it raised from S$25 in December 2025. As a Visa Infinite Metal cardholder, that fee is waived on all your pooled UNI$, including those earned on other UOB cards.
If you’re already earning UNI$ on the bank’s 4 mpd cards, that’s a very useful feature. Transfer once a quarter and you’ll avoid S$108 a year in fees, but more importantly you can transfer smaller batches as often as you like without feeling a sting each time, instead of saving up a larger balance to make each fee seem more worthwhile.
↥ Is there a minimum transfer amount?
Transfers to KrisFlyer and Asia Miles start at UNI$5,000 (10,000 miles), and must be made in blocks of that size.
If you’re just short of the next block, the UOB Payment Facility can be a quick way to top up.
How long do transfers take?
UOB quotes up to five working days for KrisFlyer and up to 14 working days for Asia Miles.
In our experience, KrisFlyer transfers usually complete within one to two days. Asia Miles transfers really do take most of UOB’s quoted window though, so don’t leave them until the last minute if you have a specific award in mind.
Instant transfers to KrisFlyer via Kris+
If you need KrisFlyer miles immediately, you can link UOB Rewards to the Kris+ app and convert as little as UNI$1,000 into 1,700 KrisPay miles, then move those 1:1 into KrisFlyer straight away.

That’s a 15% haircut compared with a normal transfer, effectively cutting the card’s earn rates to 1.19 mpd locally and 2.04 mpd overseas. With regular transfers free on this card, there’s even less reason to use it unless you need miles urgently to secure an award seat.
Remember to move the KrisPay miles into KrisFlyer within 21 days, and don’t spend any of them in Kris+ first, or the whole batch gets stuck there.
Points rounding
Like other UOB cards, the VI Metal awards UNI$ per complete S$5 of each transaction, then rounds any fraction of a UNI$ down.
Local spend earns UNI$3.5 per S$5, so an odd number of S$5 blocks leaves you with half a UNI$, which is also rounded down. For example, S$15 should earn UNI$10.5, but you’ll only get UNI$10.
Overseas spend earns a whole UNI$6 per S$5, so it avoids that problem, though anything above the last full S$5 still earns nothing.
| UNI$ awarded | ||
| SGD Charge |
Local (1.4 mpd) |
FCY (2.4 mpd) |
| S$4.99 | 0 (0 mpd) |
0 (0 mpd) |
| S$5.00 | 3 (1.2 mpd) |
6 (2.4 mpd) |
| S$9.99 | 3 (0.6 mpd) |
6 (1.2 mpd) |
| S$10.00 | 7 (1.4 mpd) |
12 (2.4 mpd) |
| S$14.99 | 7 (0.93 mpd) |
12 (1.6 mpd) |
| S$15.00 | 10 (1.33 mpd) |
18 (2.4 mpd) |
| S$20.00 | 14 (1.4 mpd) |
24 (2.4 mpd) |
For local spend, S$10 blocks are the sweet spot. The impact fades as transactions get larger, so S$249.99 of local spend earns UNI$171 (342 miles, 1.37 mpd), against UNI$175 (350 miles) for S$250.
Across a typical mix of local transactions between S$20 and S$100, expect an effective rate closer to 1.33 mpd than the headline 1.4 mpd. For smaller purchases, it’s best to use a card with more forgiving rounding where possible.
↥ Minimum spend to earn UNI$
With S$5 blocks, S$5.00 is the smallest transaction that earns anything, including foreign currency purchases that convert to less than S$5. Accumulated SimplyGo fares in a single calendar month are the exception, as explained above.
FCY fee / cpm overseas
UOB charges a 3.25% foreign currency transaction fee on the Visa Infinite Metal, in line with most Singapore cards.
At 2.4 mpd, that’s equivalent to paying 1.43 cents per mile on overseas spend, which puts it third among the S$120k cards, and top among those with no minimum spend attached to their overseas rate.
| Cost per mile on overseas transactions S$120k income cards (Best to worst, November 2026) |
|||
| Card | Fee | Mpd | Cost per mile |
| Maybank VI |
3.25% | 3.2^ | 1.07¢^ |
| SCVI |
3.5% | 3.0* | 1.22¢* |
| UOB VI Metal |
3.25% | 2.4 | 1.43¢ |
| DBS Vantage |
3.25% | 2.2 | 1.56¢ |
| OCBC Voyage |
3.25% | 2.2 | 1.56¢ |
| HSBC VI |
3.25% | 2.0 | 1.71¢ |
| Citi Prestige |
3.25% | 2.0 | 1.71¢ |
^ 3.2 mpd earn rate for the Maybank VI card is subject to a minimum spend of S$4,000 (any currency) in the same month
* 3 mpd earn rate for the SCVI card is subject to a minimum spend of S$2,000 (any currency) in the same statement cycle
Cost per mile accounts for an additional 0.30% ‘spread’ over money changer currency rates, and reflects miles earned on the billed amount inclusive of the fee. This doesn’t apply to all banks and all foreign currencies, so it’s a worst-case scenario.
As with any general spend card, a specialised 4 mpd card will beat this comfortably on eligible overseas spend within its monthly cap.
Airport lounge access
Lounge access was the VI Metal’s headline benefit for three years, with unlimited DragonPass visits for the cardholder plus one guest. That ended on 31st May 2026, as we reported when UOB announced the change a year earlier.
Principal cardholders now receive 12 complimentary visits per 12-month membership period, through UOB’s Airport Companion programme by DragonPass.

Here’s how the new allowance works:
- Shareable: Visits can be used by you alone or with guests, with each person deducting one visit. Bring three companions as guests and you’ll use up four visits.
- You must be there: Guests can only use the allowance when travelling with the principal cardholder.
- Supplementary cardholders get no visits of their own. Their entries come out of the principal cardholder’s 12, then are charged once those run out.
- Extra visits are charged at US$32 (~S$41) per person, or DragonPass’s prevailing rate shown in the app.
- Children under two enter free.
- No rollover: Unused visits expire at the end of each membership period.
The 12 visits run on your DragonPass membership year rather than the calendar year. Existing cardholders had their first batch credited on 1st June 2026, so check the renewal date shown in the Airport Companion app.
New cardholders should note that UOB’s terms require you to register within the first month of your card being issued, by downloading the Airport Companion app and verifying your card, so do this as soon as your card arrives. You’ll also need to re-register if your card is ever replaced with a new number.
Entry is by the QR code in the app, together with a same-day boarding pass. The programme also offers up to 25% off at participating airport restaurants and 5% off DragonPass limousine and meet-and-greet services.
The 12-visit allowance puts the VI Metal level with the Citi Prestige, which made the same cut in 2025, and 12 visits will still cover most people who travel a handful of times a year. A family of four could use the full allowance across three trips without paying anything extra. For a frequent solo traveller who relied on the old unlimited access though, it’s a big step backwards.
See our guide to cards with free airport lounge access for the full rundown.
No airport limo rides
There’s no complimentary airport transfer benefit with this card, something several rivals in the S$120k bracket still offer, albeit often with steep quarterly spend requirements attached.
We have a full rundown of which credit cards do offer this perk.
UOB Payment Facility
The UOB Payment Facility lets you charge any amount to your card, up to 95% of your credit limit, and have UOB transfer it to your bank account, no questions asked and with no bill needed.
You pay an administrative fee and earn 1 mpd (UNI$2.5 per S$5) on the amount. VI Metal cardholders pay a standard fee of 2.2%, slightly below the 2.3% charged to PRVI Miles cardholders, which means buying miles at 2.2 cents each.
That’s above what we’d normally pay for miles, but UOB discounts the fee regularly, currently to 2.0% (2 cents per mile) for VI Metal cardholders, for applications approved by 31st January 2027. That’s slightly better than the 2.1% PRVI Miles cardholders pay under the same promotion, with only UOB Reserve cardholders getting a lower rate (1.7%).

It’s most useful for topping up to the next UNI$5,000 transfer block. Be sure to request amounts in S$10 multiples, since UNI$2.5 per S$5 is rounded down on odd blocks.
Note that Payment Facility transactions don’t count towards the sign-up bonus or loyalty bonus spend targets.
UOB Travel Concierge
VI Metal cardholders get access to UOB Travel Concierge, the bank’s premium travel desk run by UOB Travel Planners, reachable on (65) 6302 5503 or at Travel.Concierge@UOBgroup.com.
Bookings made through it and paid with the card earn boosted UNI$:
- 5 mpd on customised tours
- 3 mpd on cruises and non-customised tours
These rates include the card’s base 1.4 mpd, with the bonus UNI$ credited within three months.
The concierge can also book stays under the various luxury hotel programmes it has access to, including Hyatt Privé, Mandarin Oriental Fan Club, Marriott STARS and Luminous, Shangri-La The Luxury Circle, Accor STEP and Hilton Impresario. These typically add perks like breakfast, upgrades and hotel credits.
As always with packaged travel, compare prices before you book. 5 mpd is only a good deal if the tour isn’t marked up by more than the extra miles are worth.
Golf benefits
The card comes with two Visa-funded golf benefits:
- Complimentary weekday green fees: one free green fee at Sentosa Golf Club when playing with at least one paying guest, up to four times a year (and no more than once a month)
- 50% off weekday green fees at 50 participating golf clubs across Southeast Asia, for the principal cardholder
Bookings for the complimentary green fee must be made at least five working days ahead, but no more than 14 days out, and only one booking can be active at a time. Public holidays are excluded, and you’ll still pay for buggies, caddies and other extras.
Dining benefits
VI Metal cardholders get discounts of up to 30% at a range of hotel restaurants in Singapore, most of them valid until 30th December 2026.
Participating hotels include The Fullerton and The Fullerton Bay, The Ritz-Carlton Millenia, Grand Hyatt, Sheraton Towers, Pan Pacific Singapore and Pan Pacific Orchard, plus several PARKROYAL properties. Most offers are 15 – 20% off the à la carte menu, with the biggest saving being 30% off afternoon tea at The Ritz Lounge. Four Seasons Hotel Singapore offers a welcome drink at Jiang-Nan Chun and Nobu instead.
Reservations are usually required, blackout dates apply on public holidays and special occasions, and the bill must be paid with your VI Metal card. Full details are on UOB’s card page.
Travel insurance
Charge the entire fare for your trip to the card before departure, and you’ll receive complimentary travel cover from United Overseas Insurance, extending to your spouse and dependent children. Unlike the PRVI Miles version, there’s no separate registration step.
Cover includes up to US$1,000,000 for accidental death or permanent disablement on public transport, modest payouts for travel delays, missed connections and delayed or lost luggage (generally S$100 to S$1,000 per person), and purchase protection of up to S$10,000 per purchase.
There’s no cover for overseas medical expenses, nor for trip cancellation, so this is a useful top-up rather than a replacement for a proper travel insurance policy. Award tickets are a grey area, since the policy requires the ‘entire travel fare’ to be charged to the card and says nothing about redemptions where you only pay the taxes, so don’t count on cover for those.
Full policy details are available here.
Assistance services
Principal cardholders can also call on UOB’s assistance programme, provided by Aspire Lifestyles:
- Vehicle assistance in Singapore, West Malaysia, and within 50 km of the Malaysia-Thailand border, worth up to S$100 per event, twice a year
- Home assistance, such as locksmith, electrical and plumbing call-outs, worth up to S$100 per visit, twice a year
- Travel and medical assistance on trips of up to 60 days, such as medical transfers, repatriation and translation help, up to S$50,000 per event
Costs above those limits are charged to you, but the medical evacuation cover does at least partly make up for the travel insurance not covering medical bills.
Other benefits
- Visa Infinite perks: including complimentary GHA DISCOVERY Titanium status, the Visa Luxury Hotel Collection and 24/7 Visa Infinite concierge via UOB (1800 253 2288).
- UOB Privilege Banking centres: you can bank at any of UOB’s five Privilege Banking centres and get priority service at UOB branches.
- KrisFlyer UOB Account: UOB advertises up to 6 bonus mpd for pairing the card with this account, but the bonus is capped at 5% of your monthly average balance, so it’s small change for most readers – avoid.
UOB VI Metal vs. UOB PRVI Miles
As we mentioned earlier, UOB’s own PRVI Miles cards earn the same headline rates for a much lower fee.
| UOB VI Metal vs. UOB PRVI Miles | ||
| UOB VI Metal |
 UOB PRVI Miles |
|
| Min. income | S$120,000 | S$30,000 |
| Annual fee | S$654 (never waived) |
S$261.60 (first year free, waiver on request) |
| Miles for paying the annual fee |
25,000 | None |
| Local spend | 1.4 mpd | 1.4 mpd |
| FCY spend | 2.4 mpd | 2.4 mpd (3 mpd regional) |
| Education spend | 1.4 mpd | Excluded |
| Big spender bonus | 15,000 miles at S$100,000 |
Amex only: 20,000 miles at S$80,000 |
| Lounge visits | 12 DragonPass (shareable) |
4 Priority Pass (cardholder only) |
| UNI$ transfer fee | Waived (all UOB cards) |
S$27 |
| Payment Facility (standard fee) |
2.2% | 2.3% |
| Travel accident cover | US$1,000,000 | S$500,000 (registration needed) |
| Other perks | Travel Concierge, golf, dining |
Up to 8 mpd Agoda / Expedia, 5 mpd FCY promos |
From year two onwards, if you value the VI Metal’s 25,000 annual miles at 1.8 cents each, its true cost is around S$204 a year. The PRVI Miles costs nothing if UOB grants your waiver request, or S$261.60 if it doesn’t.
So in practice you’re paying up to roughly S$200 a year extra for eight more lounge visits that can be shared with your travel companions, free transfers on all your UNI$, stronger travel insurance, and miles on education spend. If UOB refuses to waive your PRVI Miles fee, the VI Metal actually works out slightly cheaper.
Against that, the PRVI Miles earns more in Indonesia, Malaysia, Thailand and Vietnam, and has access to UOB’s twice-yearly 5 mpd overseas promotions and boosted Agoda and Expedia rates.
Of course, you can also hold both. That would give you 16 lounge visits a year, the PRVI Miles’ 3 mpd for regional trips, and free transfers for all the UNI$ earned across both cards, though you’d need to be comfortable paying the VI Metal’s fee every year.
Terms and conditions
Here are links to the full terms and conditions applicable to the UOB Visa Infinite Metal Card.
- UOB Visa Infinite Metal Card T&Cs
- Bonus Welcome Gift Promotion T&Cs
- UOB Rewards Programme T&Cs
- Travel Insurance Certificate
- DragonPass Lounge Access FAQ
Our Summary
There’s quite a lot to like about the UOB Visa Infinite Metal Card. Uncapped earn rates of 1.4 mpd locally and 2.4 mpd overseas are among the best in the S$120k bracket, 25,000 miles are credited every year when you pay the fee, and free UNI$ transfers make it a good partner for UOB’s 4 mpd cards.
Unusually, school and university fees earn miles too.
Sadly, the card has been cut back significantly over the last year. Unlimited lounge access with a guest has become 12 shared visits a year, the sign-up bonus has dropped from 80,000 to 60,000 miles, and there’s still no limo benefit.
UOB’s usual annoyances also apply – S$5 earning blocks, two-year UNI$ expiry and only two useful transfer partners. On top of that, unlike the PRVI Miles, the S$654 fee can never be waived.
Most importantly, the PRVI Miles earns at identical rates for 40% of the fee, and even beats it on regional FCY spend.
That makes the VI Metal worth considering only for new-to-UOB applicants who can tap the sign-up bonus, those paying school fees or seeking shareable lounge visits, and UOB 4 mpd card users who’ll make good use of the free transfers.
For most other S$120k earners, it’s hard to justify over a PRVI Miles card, unless you plan to hold both.
| Our Rating | ||||||||||||||||||||
| 2.5 / 5 among high income general spend cards |
||||||||||||||||||||
|
UOB Visa Infinite Metal |
||||||||||||||||||||
How we rate credit cards
|
||||||||||||||||||||
Links on Mainly Miles may pay us an affiliate commission.