
Here’s our review of the HSBC Premier Mastercard issued in Singapore. It forms part of our series of credit card reviews, which are all summarised on our dedicated Credit Cards page.
Dollar amounts refer to SGD, and ‘miles’ assume HSBC’s 2.5:1 airline transfer partners, except where stated. This review was updated on 30th October 2026.
| HSBC Premier Mastercard | |||
 |
1.68 mpd local |
2.76 mpd FCY |
Unlimited lounge visits |
| APPLY HERE | |||
| HSBC Premier Mastercard | ||
|
||
|
1.68 mpd local |
2.76 mpd FCY |
Unlimited lounge visits |
| APPLY HERE | ||
Mainly Miles Says
The HSBC Premier Mastercard earns 1.68 mpd on local spend, the best of any general spend card in Singapore, and 2.76 mpd overseas, with no cap and no minimum spend. There are also unlimited lounge visits for you and up to three supplementary cardholders, up to eight airport limo rides a year and free, instant transfers to 20 loyalty partners – so it’s a very strong package.
The difficult part is getting one. The card is only available to HSBC Premier customers, which means keeping at least S$200,000 with the bank, and the return you could be earning on that money elsewhere is the card’s hidden cost. Fall below the minimum and you’ll face a hefty S$708.50 annual fee.
KrisFlyer addicts should also factor in HSBC’s poorer 3:1 ratio, which trims the earn rates to 1.4 mpd and 2.3 mpd for SIA’s programme – still level with the best on local spend, but trailing a few rivals on the FCY side.
| Pros | Cons |
|
|
If you’re already an HSBC Premier customer, and this isn’t your default card for general spend, there’s no two ways about it – it should be!
If you’re not, the decision is really about where you’d put S$200,000. Let’s take a look.
Eligibility
- Minimum Age: 21
- Banking relationship: HSBC Premier (required)
| Minimum Income | ||
| Applicant | With HSBC TRB S$50,000+ |
Everyone else |
| Singaporean / PR (salaried) |
S$30,000 | S$65,000 |
| Singaporean / PR (self-employed / on commission) |
S$40,000 | S$65,000 |
| Foreigner | S$65,000 | S$65,000 |
For once, income is the easy part.
HSBC Premier requires a Total Relationship Balance (TRB) of at least S$200,000. That clears the S$50,000 TRB threshold for HSBC’s lower income bands with plenty to spare. In practice, then, it’s S$30,000 a year for salaried Singaporeans and PRs, or S$40,000 if you’re self-employed or on commission. Foreigners need S$65,000 regardless.
A secured version, backed by a fixed deposit of at least S$10,000, is also available. That seems a little pointless here, since the S$200,000 balance is the real hurdle.
The S$200,000 question
The true entry requirement is the HSBC Premier relationship itself, which means keeping a TRB of at least S$200,000 with HSBC Singapore.
That doesn’t all have to sit as cash. Deposits count, and so do investments held through HSBC and the surrender value of insurance policies. HSBC’s TRB guide has the full breakdown.
What you do with that money is the key factor. Every 1% a year of return you give up on S$200,000 costs you S$2,000, nearly three times the S$708.50 annual fee the balance is saving you.
Leave it in a low-interest account and the card is far from free – you’re simply paying for it in a less obvious way.
Hold it in investments you’d want to own anyway, and most of that cost disappears. Bear in mind that HSBC earns commission on many of the products its Relationship Managers recommend, insurance and structured products in particular, so don’t take every suggestion at face value.
HSBC also runs separate welcome rewards for customers bringing fresh funds into Premier, which can soften the cost in year one. These change frequently, so check HSBC’s Premier offers page before you move any money.
Annual Fees & Interest Rates
- Annual Fee (principal): S$708.50 (waived for Premier Qualified customers)
- Annual Fee (supplementary): Free (up to three cards)
- Fee waiver: automatic with a Premier relationship and a S$200,000+ TRB, or an HSBC Singapore Private Banking relationship
The fee rose from S$490.50 to S$708.50 on 19th August 2025, as part of the card’s major refresh. For Premier Qualified customers it’s academic, because the waiver is assessed year by year and applies for as long as the relationship and balance stay in place.
The first year’s fee isn’t charged straight away. It’s billed three calendar months after the month your card account was opened, then in that anniversary month each year after.
Up to three supplementary cards are free for life, for anyone aged 18 or over. Their spend earns points into your account, and as we’ll see, each one carries its own unlimited lounge access.
Other fees and interest rates for the HSBC Premier Mastercard include:
- EIR: 27.8%
- Interest-free period: 20 days from statement date
- Minimum payment: 3% (min. S$50, or balance if less)
- Late payment fee: S$100
- Cash advance fee: 8% (min. S$15)
- Overlimit fee: S$40
When the fee isn’t waived
The S$708.50 fee mostly hits Premier customers whose TRB has slipped below S$200,000.
Premier status isn’t withdrawn the moment your balance dips, but the account starts attracting a monthly fall-below fee, and the card’s annual fee comes back into play too.
Unlike the TravelOne or Citi PremierMiles, there are no miles for paying the fee, so you’re paying for the perks alone.
The big one is lounge access. Value each visit at the US$35 (~S$45) Priority Pass guest rate, and you’d need around 16 visits a year across your four cards to break even, before counting limo rides or the earn rate.
Don’t expect to talk your way out of the fee and keep the perks, either. The card’s terms are explicit – cardholders who don’t qualify for the waiver and don’t pay the fee aren’t entitled to any of the card’s benefits, lounge and limo access included. HSBC can also bill the cash value of any benefits already used.
A frequent-flying family might make the fee pay. For most, restoring the balance (or cancelling) makes more sense than paying.
Sign-up bonus
HSBC has run a welcome offer on the Premier Mastercard almost continuously since its 2025 refresh. Unusually, it’s open to existing HSBC cardholders too, provided you don’t currently hold a principal Premier Mastercard and haven’t cancelled one in the past 12 months.
The current offer, for applications submitted by 31st October 2026, requires S$5,000 of qualifying spend from account opening to the end of the following month:
- Premier Qualified customers: 58,200 miles (145,500 Reward points), plus a S$200 Apple voucher, with the annual fee waived
- Non-Premier Qualified customers: 34,200 miles (85,500 Reward points), plus the same voucher, with the S$708.50 fee payable
The voucher is limited to the first 800 customers to complete the spend, but the bonus miles are uncapped. You’ll also need to give marketing consent during your application.
Bonuses have ranged widely, from 106,200 miles when the refreshed card launched in August 2025, to 91,800 miles for much of the first half of 2026, to today’s lower level. If you’re not in a hurry, it can pay to wait for a better round.
We’ve covered the current offer in full, including the voucher’s quirks and the qualifying spend windows, here.
Offers change regularly, so check our Sign-Up Bonuses page for the latest rundown across miles-earning cards.
Regular earn rates
The HSBC Premier Mastercard earns:
- 1.68 mpd on local spend in SGD (4.2 Reward points per S$1)
- 2.76 mpd on spend in foreign currency (6.9 Reward points per S$1)
There’s no minimum spend and no cap. Those points are made up of a 1x base award plus a 3.2x (local) or 5.9x (FCY) bonus, which affects rounding, as we’ll examine later.
At our 1.8 cent valuation, that’s like getting around 3% back on local spend and close to 5% overseas (before the FCY fee). That’s very decent for a card with no bonus categories, caps or registration to worry about.
HSBC itself advertises 1.4 mpd and 2.3 mpd, because it assumes a KrisFlyer transfer at 3:1. The local rate still matches the best of any other general spend card. Overseas, though, 2.3 mpd is overtaken by several rivals.
Earn rates (general spend cards)
(Best to worst, October 2026)
| Card | Local Spend | FCY Spend |
| HSBC PMC (2.5:1 partners) |
1.68 mpd | 2.76 mpd |
 BOC EM |
1.4 mpd | 2.8 mpd |
 UOB PRVI Miles |
1.4 mpd | 2.4 mpd |
| HSBC PMC (KrisFlyer) |
1.4 mpd | 2.3 mpd |
 DBS Altitude |
1.3 mpd | 2.2 mpd |
 OCBC 90oN |
1.3 mpd | 2.1 mpd |
 HSBC T1 (2.5:1 partners) |
1.2 mpd | 2.4 mpd |
 Citi PM |
1.2 mpd | 2.2 mpd |
 SC Journey |
1.2 mpd | 2 mpd |
 KF Ascend |
1.2 mpd | 1.2 mpd |
 KF UOB |
1.2 mpd | 1.2 mpd |
 KF Blue |
1.1 mpd | 1.1 mpd |
| HSBC T1 (KrisFlyer) |
1 mpd | 2 mpd |
Spend S$1,500 in SGD and S$500 in foreign currency each month, and the Premier Mastercard earns 46,800 miles a year with a 2.5:1 partner, comfortably ahead of every other card here.
Transfer to KrisFlyer and it’s 39,000 miles, just behind the UOB PRVI Miles (39,600) and the BOC Elite Miles (42,000) on the same spend. The more of your spend is local, the better the Premier Mastercard looks against those two.
What counts as overseas spend?
HSBC’s terms define local spend as anything charged in the card’s own currency, and overseas spend as anything charged in another currency. The 2.76 mpd rate depends purely on the billing currency. Where the merchant or its payment processor is located doesn’t come into it.
That works both ways. An online purchase billed in USD earns the overseas rate even if the merchant is in Singapore, while anything charged in SGD earns 1.68 mpd, even in a shop in Tokyo.
Dynamic currency conversion, where a merchant offers to bill you in SGD, therefore costs you a worse exchange rate and around 40% of your miles. Always pay in the local currency.
The USD version
HSBC also issues a USD-denominated Premier Mastercard under the same terms, billed in USD with an annual fee of US$545. Here, it’s the other way round:
- USD spend earns the ‘local’ rate, at 4.2 points per US$0.70.
- Anything not in USD, SGD included, earns the overseas rate.
- The overseas education benefit below doesn’t apply.
Because the earn rate is pegged at US$0.70 to S$1, its real value moves with the exchange rate. It’s a niche product for people who already earn or spend in USD, so the rest of this review covers the SGD card.
Overseas education
Since 23rd July 2026, the Premier Mastercard has also earned the full 2.76 mpd (2.3 mpd KrisFlyer) on school, college and university fees charged in foreign currency, as we reported in September. There’s no cap and no minimum spend.

That’s notable, because HSBC removed education from rewards earning across its cards in 2020, and most other Singapore banks exclude it too.
A few points to bear in mind:
- Local fees still earn nothing. School or university fees charged in SGD remain fully excluded.
- Check the currency. An overseas institution that bills you in SGD earns no points at all, so always pay in its local currency.
- Watch for surcharges. Some institutions add 2-3% for card payments, which on top of the 3.25% FCY fee can make miles on tuition an expensive exercise.
HSBC has done this with a standalone clause awarding points on the six education MCCs, rather than removing them from the card’s exclusion list. So education still sits outside the card’s definition of “Qualifying Transactions”.
That has a knock-on effect – by the letter of the terms, tuition payments earn points but don’t count towards the S$12,000 quarterly spend for limo rides.
Pairing with the HSBC Revolution
With no bonus categories of its own, the Premier Mastercard works best alongside the HSBC Revolution. The Revolution is fee-free, and earns 4 mpd on eligible online and contactless spend, or 8 mpd if you keep S$50,000 in an HSBC Everyday Global Account.
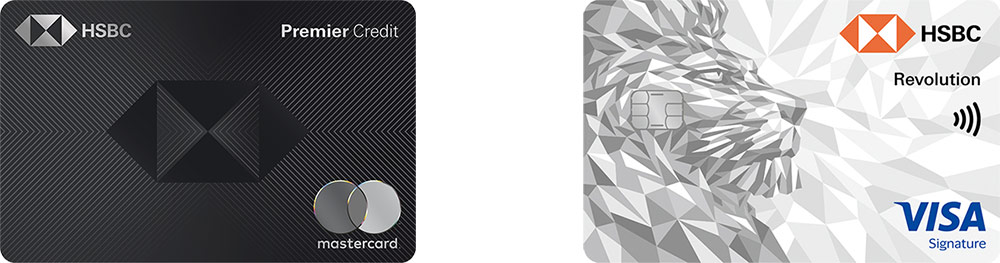
As a Premier customer, you’ll already hold the Everyday Global Account that unlocks that higher tier.
Because HSBC points pool, the two cards feed a single balance with the same 20 transfer partners. Here’s how to split your spend:
- Revolution for dining, retail, ride-hailing and direct airline and hotel bookings, paid online or by tapping the card, up to its S$1,000 monthly bonus cap (S$1,200 with the EGA)
- Premier Mastercard for everything else, including foreign currency spend outside the Revolution’s categories or beyond its cap
If you hold the Premier Mastercard, there’s little reason to keep a TravelOne as well. The Premier card out-earns it on every transaction and has far better lounge access.
Eligible transactions
Reward points are awarded on posted retail purchases. The Premier Mastercard’s terms exclude 48 merchant category codes, in line with HSBC’s other cards, and apart from the education carve-out above, these earn nothing at all. The main categories are:
- Bills and top-ups: utilities, payment service providers, money transfers, and stored-value or e-wallet top-ups such as GrabPay and YouTrip
- Insurance: premiums, underwriting and direct-marketed insurance
- Healthcare and local education: hospitals, plus schools and universities billed in SGD
- Government: tax, court costs, fines, bail, postal and other government services
- Property and parking: rent paid through real estate agents, cleaning and maintenance (including property management fees), and car parks
- Financial: cash disbursements, brokerages, forex, crypto and other quasi-cash transactions
- Organisations: charities, plus religious and political organisations
- Catch-alls: professional services, business services and ‘other services’ not classified elsewhere, plus nondurable goods wholesalers
- Gambling: betting, lotteries and online casinos
HSBC’s wider Rewards Programme terms also exclude payment platforms like CardUp, ipaymy and SmoovPay, so you can’t route rent or tax through them for miles.
Watch out for the ‘catch-all’ codes in particular, MCC 7299 and 7399, which cover a surprisingly wide range of merchants. If a regular payment seems to be earning nothing, the HSBC Singapore app shows the MCC against completed transactions.
On the plus side, purchases converted to an HSBC Spend Instalment plan earn points on the full purchase amount, in the month you make it.
The full list of exclusions is in the card’s terms and conditions.
Posting date, not transaction date
HSBC counts your spend by the date it posts to your account, usually a day or two after you make the purchase.
That matters most for the sign-up bonus and the quarterly limo spend. A purchase on the last day of a qualifying period can easily post outside it, so leave yourself a few days’ margin.
When do points credit?
Both base and bonus points are credited as each transaction posts, usually within a few days. There’s no monthly lump sum to wait for, unlike the Revolution’s bonus points.
Refunded or reversed transactions have their points clawed back. If you’ve already transferred those points out, HSBC can charge their cash value to your card instead.
Points rounding
HSBC’s terms state that points are rounded to the nearest whole number. Based on cardholder-reported data, HSBC calculates the 1x base points and the 3.2x or 5.9x bonus points separately for each transaction, rounding each before adding them together.
A S$7.80 coffee and cake, for example, earns 8 base points plus 25 bonus points (24.96, rounded up), for 33 points, or 13.2 miles. That’s 1.69 mpd, slightly above the headline rate.
There are no spending blocks to lose out on, so small and odd-sized transactions earn the full rate or a touch more. That’s a real advantage over cards that round down to the dollar or earn in S$5 blocks.
↥ Minimum spend to earn points
With both parts rounded to the nearest point, the smallest local charge earning anything is S$0.16, where the 3.2x bonus rounds up to a single point. In foreign currency it’s the equivalent of just S$0.09.
FCY fee / cpm overseas
HSBC charges 3.25% on foreign currency transactions, in line with most of the market in Singapore.
At 2.76 mpd, that means buying miles at 1.24 cents each on overseas spend with a 2.5:1 partner, well below the 1.8 cents we value a mile at. Transfer to KrisFlyer, and it rises to 1.49 cents per mile.
| Cost per mile on overseas transactions (general spend cards) (Best to worst, October 2026) |
|||
| Card | Fee | Mpd | Cost per mile |
| BOC EM |
3% | 2.8 | 1.14¢ |
| UOB PRVI Miles (IDR, MYR, THB, VND) |
3.25% | 3.0 | 1.14¢ |
 Maybank HVS |
3.25% | 2.8* | 1.22¢* |
 SCVI |
3.5% | 3.0** | 1.22¢** |
| HSBC PMC (2.5:1 partners) |
3.25% | 2.76 | 1.24¢ |
| HSBC T1 (2.5:1 partners) |
3.25% | 2.4 | 1.43¢ |
| UOB PRVI Miles (other currencies) |
3.25% | 2.4 | 1.43¢ |
| HSBC PMC (KrisFlyer) |
3.25% | 2.3 | 1.49¢ |
| Citi PM |
3.25% | 2.2 | 1.56¢ |
| DBS Altitude |
3.25% | 2.2 | 1.56¢ |
 OCBC Voyage |
3.25% | 2.2 | 1.56¢ |
 OCBC 90oN |
3.25% | 2.1 | 1.63¢ |
| HSBC T1 (KrisFlyer) |
3.25% | 2.0 | 1.71¢ |
 HSBC VI |
3.25% | 2.0 | 1.71¢ |
| SC Journey |
3.5% | 2.0 | 1.83¢ |
| KF UOB |
3.25% | 1.2 | 2.86¢ |
| KF Ascend |
3.25% | 1.2 | 2.86¢ |
| KF Blue |
3.25% | 1.1 | 3.12¢ |
* Maybank Horizon Visa Signature: minimum S$800 spend per calendar month required.
** Standard Chartered Visa Infinite: minimum S$2,000 spend per statement period required.
Cost per mile accounts for an additional 0.30% ‘spread’ over money changer currency rates. This doesn’t apply to all banks and all foreign currencies, so it’s a worst-case scenario.
Only four options come in cheaper:
- the BOC Elite Miles
- the PRVI Miles’ regional rate
- two cards needing a monthly minimum spend: the Maybank Horizon Visa Signature and SCVI
Among cards with no strings attached, the Premier Mastercard is the cheapest way to earn miles in most foreign currencies.
What does it cost to transfer?
Nothing. Conversions are made in the HSBC Singapore app, free of charge “until such time as may be determined by HSBC”.
HSBC has flirted with charging before, announcing a 10,000-point fee per conversion in 2023 before shelving it. Free transfers are a big plus for HSBC’s cards today, but that wording means the bank could bring back a fee at any time.
Which loyalty schemes can I transfer into?
HSBC Reward points convert to 16 airline programmes and four hotel loyalty schemes, the widest choice of any Singapore bank. Unfortunately, many of them come with worse conversion ratios, so here’s how each partner affects the card’s effective earn rates.
| HSBC Points to Airline Miles |
||||
| FFP |
Ratio | Effective Earn Rate | ||
| Local | FCY | |||
 |
Air France / KLM Flying Blue |
2.5:1 | 1.68 mpd | 2.76 mpd |
 |
British Airways Club |
2.5:1 | 1.68 mpd | 2.76 mpd |
 |
Cathay Pacific Asia Miles |
2.5:1 | 1.68 mpd | 2.76 mpd |
 |
Etihad Guest |
2.5:1 | 1.68 mpd | 2.76 mpd |
 |
EVA Air MileageLands |
2.5:1 | 1.68 mpd | 2.76 mpd |
 |
Qantas Points |
2.5:1 | 1.68 mpd | 2.76 mpd |
 |
Vietnam Airlines Lotusmiles |
2.5:1 | 1.68 mpd | 2.76 mpd |
 |
Singapore Airlines KrisFlyer |
3:1 | 1.4 mpd | 2.3 mpd |
 |
Thai Airways Royal Orchid |
3:1 | 1.4 mpd | 2.3 mpd |
 |
Air Canada Aeroplan |
3.5:1 | 1.2 mpd | 1.97 mpd |
 |
Hainan Airlines Fortune Wings |
3.5:1 | 1.2 mpd | 1.97 mpd |
 |
Qatar Airways Privilege Club |
3.5:1 | 1.2 mpd | 1.97 mpd |
 |
Turkish Airlines Miles&Smiles |
3.5:1 | 1.2 mpd | 1.97 mpd |
 |
United Airlines MileagePlus |
3.5:1 | 1.2 mpd | 1.97 mpd |
 |
Japan Airlines Mileage Bank |
5:1 | 0.84 mpd | 1.38 mpd |
 |
AirAsia Rewards |
1.25:1 | 3.36 ppd* | 5.52 ppd* |
* AirAsia Rewards points aren’t miles, and they’re worth considerably less. The favourable-looking ratio and ppd rates sadly don’t translate into good value.
| HSBC Points to Hotel Points |
||||
| Programme |
Ratio | Effective Earn Rate | ||
| Local | FCY | |||
 |
IHG One Rewards |
2.5:1 | 1.68 ppd | 2.76 ppd |
 |
Marriott Bonvoy |
2.5:1 | 1.68 ppd | 2.76 ppd |
 |
Wyndham Rewards |
3:1 | 1.4 ppd | 2.3 ppd |
 |
Accor ALL |
5:1 | 0.84 ppd | 1.38 ppd |
The seven 2.5:1 airline partners are where the card earns as advertised, and between them they cover all three alliances:
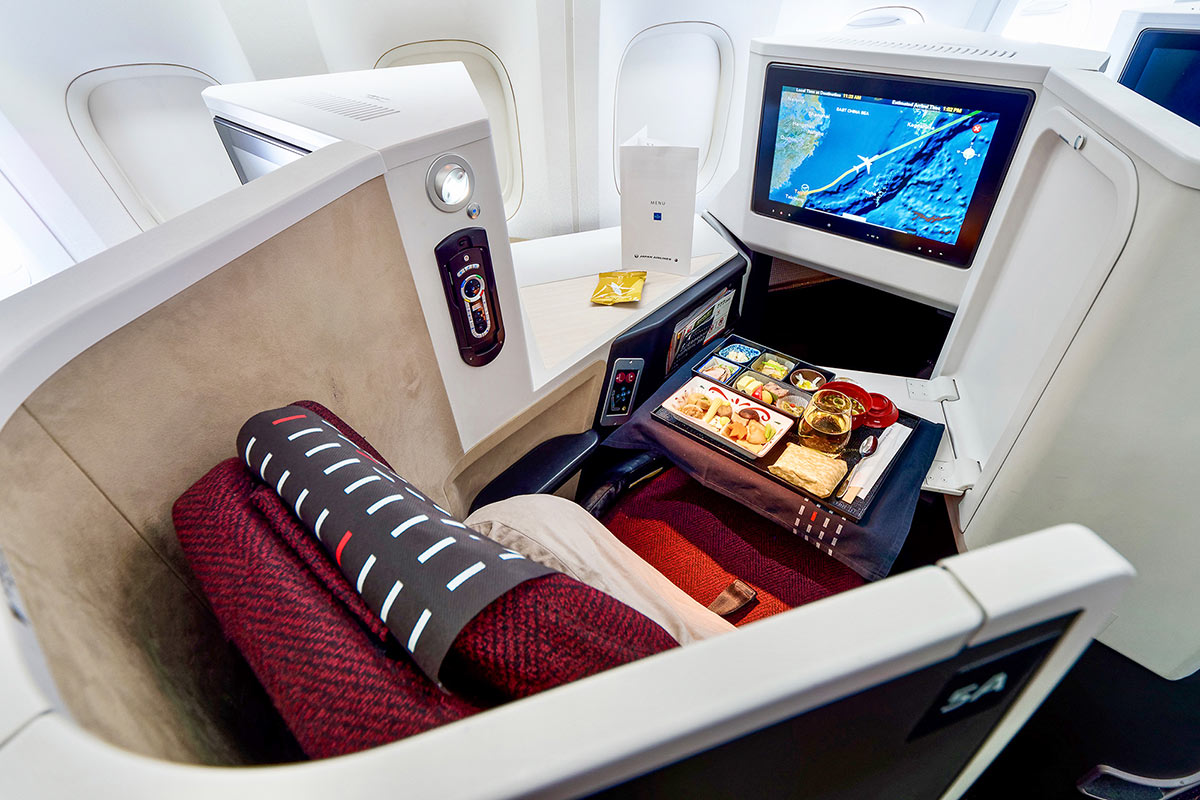
- Asia Miles and British Airways Avios for oneworld, including Cathay Pacific, Qantas, Japan Airlines and Finnair awards
- Flying Blue for SkyTeam
- EVA Air Infinity MileageLands, the only 2.5:1 option in Star Alliance
- Qantas, Etihad and Vietnam Airlines for more specific redemptions
Don’t transfer directly to Qatar Airways Privilege Club. At 35,000 points per 10,000 Avios, it takes 40% more points than going via British Airways at 25,000, then moving the Avios across 1:1.
Star Alliance flyers have a tougher choice. KrisFlyer and Thai Royal Orchid Plus convert at 3:1, while Aeroplan, United and Turkish are all 3.5:1, which drops the card to 1.2 mpd locally. Each has its sweet spots, but you’ll want a specific redemption in mind before accepting that haircut.
JAL Mileage Bank, at 5:1, is best ignored, and AirAsia points aren’t miles at all.
(Photo: Melvin Loi)
On the hotel side, IHG and Marriott at 2.5:1 are the pick on ratio, though hotel points generally deliver poorer value than airline transfers.
↥ Is there a minimum transfer amount?
Each transfer must be at least 10,000 miles. That’s 25,000 points at 2.5:1, or 30,000 for KrisFlyer.
Above that minimum you can transfer in increments of just 2 miles, ideal for clearing out awkward balances.
A year of our S$1,500 local and S$500 FCY example, for instance, leaves you with 117,000 points. That converts to exactly 46,800 Asia Miles or Avios, or exactly 39,000 KrisFlyer miles, with nothing left over.
How long do transfers take?
Instantly, for all but two partners. Hainan Fortune Wings Club takes up to five working days, and JAL Mileage Bank up to ten.
That means you can spot an award seat and lock it in with points in the same sitting, something most Singapore credit cards still can’t offer.
Instant transfers to KrisFlyer
KrisFlyer transfers are instant too. That’s still rare in Singapore – DBS, UOB and Citi cardholders, for example, can only get KrisFlyer miles immediately by routing their points through Kris+, with a 15% haircut on the transfer ratio.
The irony here is that the 3:1 ratio carries a similar penalty, 17% against a 2.5:1 transfer. So every KrisFlyer conversion from this card is effectively priced like an emergency one is from other cards!

Do HSBC Reward points expire?
Yes, at the end of a 37-month period beginning the month after they are earned. That’s three years and one month of validity, so points earned in October 2026 expire on 30th November 2029.
With free, instant transfers in 2-mile increments, that’s rarely a problem in practice. Just don’t move points out early without a redemption in mind, as your miles’ own expiry clock then starts.
HSBC Reward points pool
Since May 2024, points from all your HSBC credit cards sit in a single balance, so Premier Mastercard and Revolution points can be combined in one transfer.
There’s a catch if you later cancel one of the cards. HSBC redeems points on a first-in-first-out basis, and points earned on a closed card are forfeited.
This is most likely to be an issue if your TRB falls short and you decide to drop the Premier Mastercard rather than pay the fee. Transfer out everything you need first, or the card’s share of your balance could be lost.
What else can HSBC points be used for?
Plenty, but none of it comes close to converting to miles.
At 2.5:1, and valuing a mile at 1.8 cents, an HSBC Reward point is worth around 0.72 cents. Compare that with:
- Travel with Points, HSBC’s portal for flights, hotels and car rental, currently at a promotional 250 points per S$1, or 0.4 cents per point
- Pay with Points, to offset card spend, at 0.25 cents per point
- Vouchers and merchandise in the rewards catalogue, which typically price below that
The exception, as with any card, is a balance you’d otherwise forfeit.
Airport lounge access
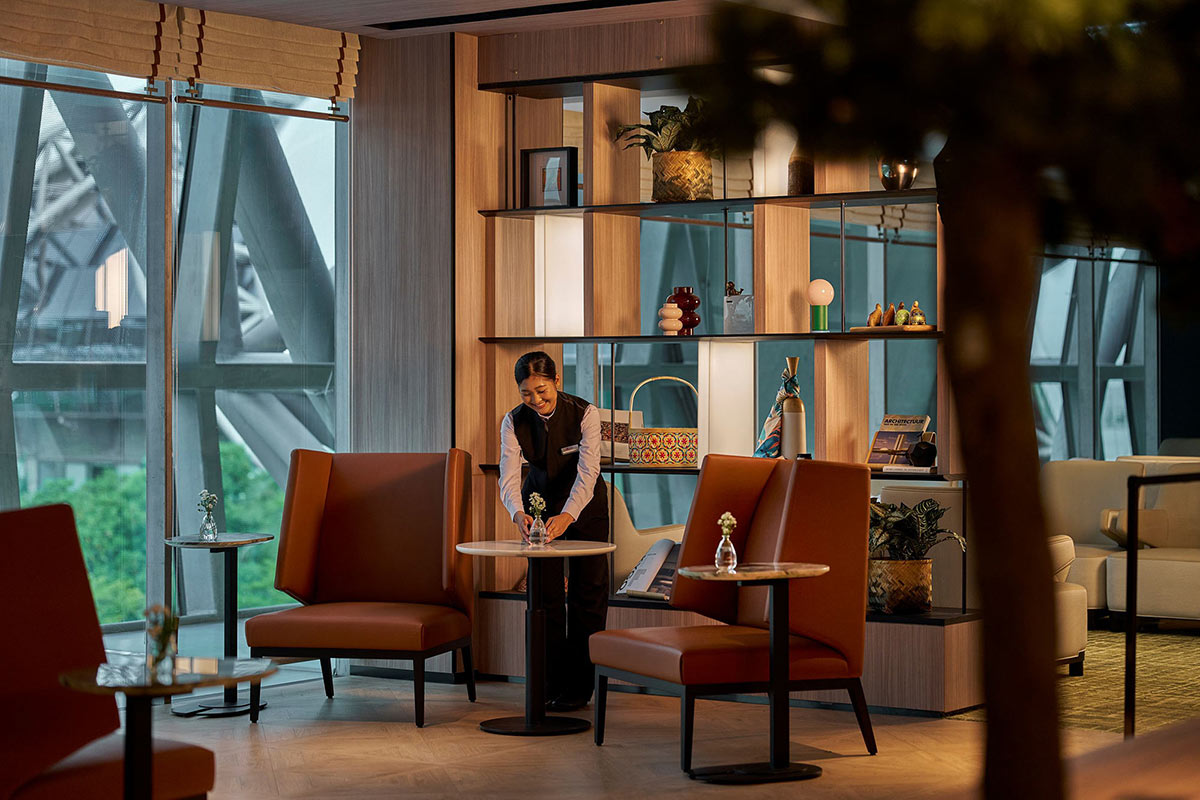
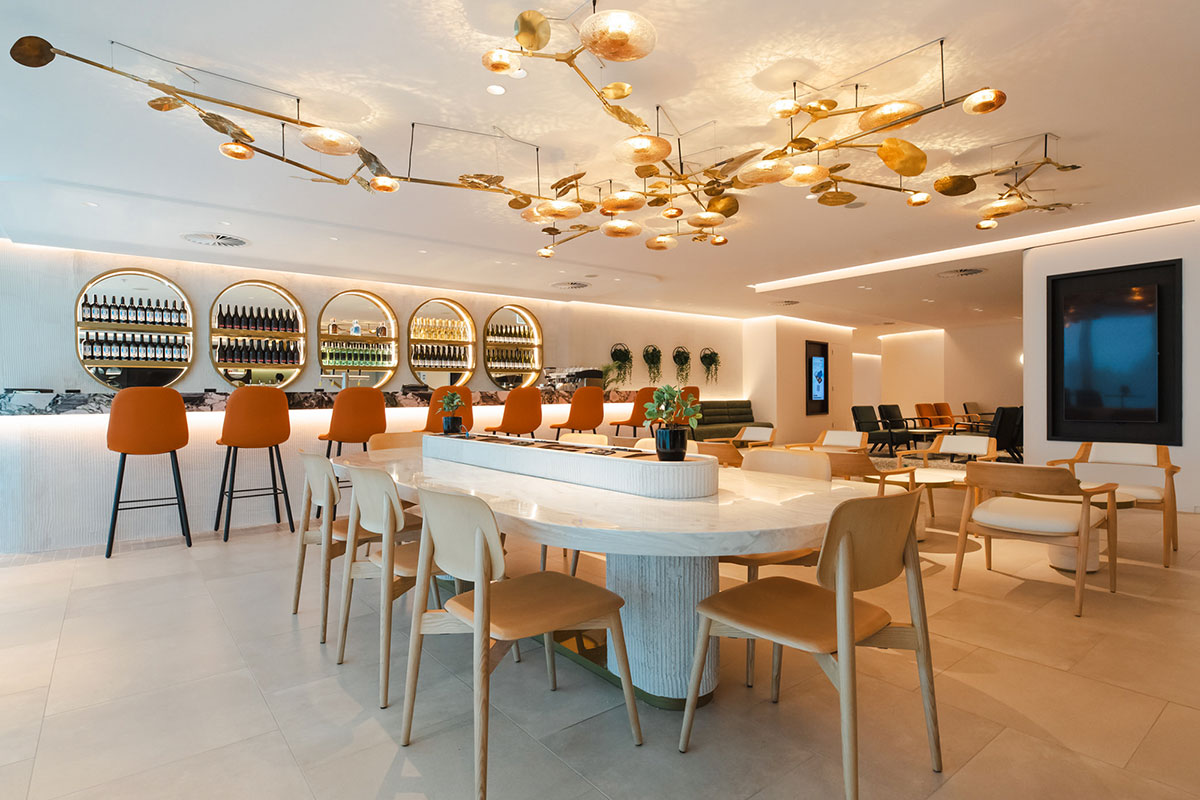
This is arguably the Premier Mastercard’s best perk. The principal cardholder and up to three supplementary cardholders each get unlimited Priority Pass lounge visits, with no annual fee for Premier Qualified customers.
(Photo: Plaza Premium)
The details:
- There’s no separate membership card to carry. Present your physical Premier Mastercard and boarding pass, ask for Priority Pass access under the HSBC Premier Mastercard, and sign the visit slip.
- Some lounges may place a US$1 pre-authorisation on your card to verify it. This isn’t charged.
- Guests aren’t included, and are charged US$35 per visit, billed to whoever signs them in.
- Supplementary cardholders must be at least 18, and can use their access independently, without the principal cardholder travelling.
- The terms only cover participating airport lounges, so don’t count on using the benefit at Priority Pass restaurants, spas or other non-lounge experiences.
Because guests aren’t covered, the way to share the benefit is through the supplementary cards. A couple with two adult children, for example, can cover the whole family.
Very few Singapore cards extend unlimited visits beyond the principal cardholder, and none we know of do so without an annual fee.
The terms set the benefit’s validity as 19th August 2025 to 31st December 2026, “or such other date as determined by HSBC”. It has only improved since 2024, but it’s worth checking it carries over into 2027.
Airport limo rides
Primary cardholders can earn two complimentary airport limo transfers per calendar quarter, up to eight a year, between any agreed address in Singapore and Changi.
| HSBC Premier Mastercard airport limo rides | ||
| Customer | Requirement | Rides |
| Premier | S$12,000 spend (previous calendar quarter) |
2 per quarter |
| New cardholders | S$6,000 spend (in the quarter the card is issued) |
2 |
| Premier Elite | No minimum spend (average TRB of S$1.2 million+ in the previous quarter) |
2 per quarter |
Only Qualifying Transactions count towards the spend thresholds, so anything on the card’s exclusion list, overseas education included, won’t help.
Rides aren’t instant either. HSBC issues codes up to two months after each quarter ends, so January to March spend unlocks rides by 31st May.
Codes are then valid for up to a year, and you book through HSBC’s limo portal.
The conditions are fairly standard:
- The primary cardholder must be on a flight departing from or arriving at Changi.
- Only one booking can be outstanding at a time.
- Cancellations need 24 hours’ notice, or the ride is forfeited.
- HSBC recommends booking at least 48 hours ahead.
- Extra stops aren’t allowed.
- Surcharges apply for child seats, certain zones, and midnight or early-hour pickups.
S$12,000 a quarter is a lot of spend, around S$4,000 a month. On this card it earns over 20,000 miles a quarter in its own right, so think of the rides as a bonus for heavy spenders. It’s not a reason to divert spend that would earn 4 mpd elsewhere.
The lower S$6,000 threshold in your first quarter is easier to hit, especially alongside a sign-up bonus spend target.
Travel insurance
Charge your full air fare to the card, or redeem your flights with points earned on it, and complimentary travel insurance from AIG kicks in. It covers you, your spouse, up to three children and a domestic helper, whether you’re travelling together or not, on trips of up to 180 days starting from Singapore.
| HSBC Premier Mastercard complimentary travel insurance | |
| Benefit | Maximum (cardholder) |
| Accidental death / permanent disablement (on a common carrier) |
US$500,000 |
| Overseas medical expenses | US$500,000 |
| Emergency medical evacuation / repatriation | US$500,000 |
| Trip cancellation / curtailment | US$7,500 |
| Trip delay (4 hours+) |
US$500 |
| Loss of luggage | US$3,000 |
| Luggage delay (4 hours+) |
US$500 |
| Personal liability | US$500,000 |
Note: Limits are roughly halved for your spouse, and are lower still for children and domestic helpers.
That’s a far more substantial policy than the TravelOne’s, with medical cover more than four times higher, plus personal liability. The usual caveats apply: cardholders must be aged 18 to 69, and pre-existing medical conditions aren’t covered. As always, read the policy wording before relying on it in place of a standalone policy.
Other benefits
- World Elite Mastercard benefits, for principal and supplementary cardholders:
- Hotel status: Brilliant by Langham Ruby, Centara Platinum, GHA DISCOVERY Titanium, I Prefer Titanium, My Millennium Prestige and ONYX Platinum
- Avis President’s Club
- An annual 3GB Flexiroam data package
- HoteLux Elite Plus membership
- A complimentary night at selected hotel chains through Mastercard
- HSBC Premier Mastercard Concierge: travel, dining and lifestyle assistance on 1800 227 8889, from restaurant and hotel bookings to event tickets and gift delivery
- Premier Destinations: ‘Stay 2 Pay 1’ offers at participating hotels. The current round is a free second night at four Mandarin Oriental properties until 31st December 2026, covered here.
- Dining:
- 1-for-1 HSBC PALATE set menus at a rotating list of Singapore restaurants
- Savour Dining experiences
- Priority Friday and Saturday reservations at Burnt Ends until 31st December 2026
- Apple Store for HSBC Premier: up to 5% cashback on selected devices, through Apple reseller CarltonOne
- Golf: six complimentary games a year at participating clubs in Asia, for Premier Elite customers only
- Health and wellness: a 24/7 health concierge and partner rates on screenings and consultations. These come with HSBC Premier itself rather than the card.
- Mastercard Travel Rewards and Priceless Specials: cashback offers abroad, plus concert presales and other Mastercard experiences
Terms and conditions
Here are links to the full terms and conditions applicable to the HSBC Premier Mastercard and the HSBC Rewards programme.
- HSBC Premier Mastercard T&C
- HSBC Premier Mastercard FAQs
- HSBC Premier Mastercard Sign-Up Promotion T&C
- HSBC Premier Mastercard Travel Insurance Policy
- HSBC Premier Mastercard Golf Benefit T&C
- HSBC Rewards Programme T&C
- HSBC Cardholder Agreement
Our Summary
Since swapping cashback for miles in October 2024, the HSBC Premier Mastercard has become arguably the best general spend card in Singapore.
Its 1.68 mpd local earn rate is unmatched among general spend cards, and 2.76 mpd overseas sits near the top. You get that with no caps, no minimum spend and none of the category juggling bonus cards demand.
Then there are the benefits. Unlimited lounge access for four cardholders is rare, the limo rides are a useful extra for heavy spenders, and HSBC’s free, instant transfers to 20 partners remain the most flexible in the market.
The card itself has very few weaknesses – it’s really just a question of whether you can get one!
If you’re already Premier Qualified, there’s nothing to think about. Make this your default card for anything outside your 4 mpd cards, ideally alongside the HSBC Revolution.
If you’re not, it comes down to whether moving S$200,000 to HSBC stacks up. If it’s invested in something you’d hold anyway, it can. If it’s sitting idle in a low-interest account, the hidden cost quickly outweighs the card’s value.
KrisFlyer collectors still do well, at 1.4 mpd and 2.3 mpd. To get the card’s full value, though, you need Asia Miles, Avios or another 2.5:1 partner.
It’s also worth remembering how quickly things move here. The sign-up bonus has almost halved in a year, and the lounge and limo benefits are only formally confirmed until 31st December 2026.
Today the card’s package is excellent – enjoy it while it lasts!
| Our Rating | ||||||||||||||||||||
| 4.5 / 5 among general spend cards |
||||||||||||||||||||
|
HSBC Premier Mastercard |
||||||||||||||||||||
How we rate credit cards
|
||||||||||||||||||||
(Cover Photo: Plaza Premium)
Can we have same details on SC Beyond like points rounding, fee if fall below $200k?