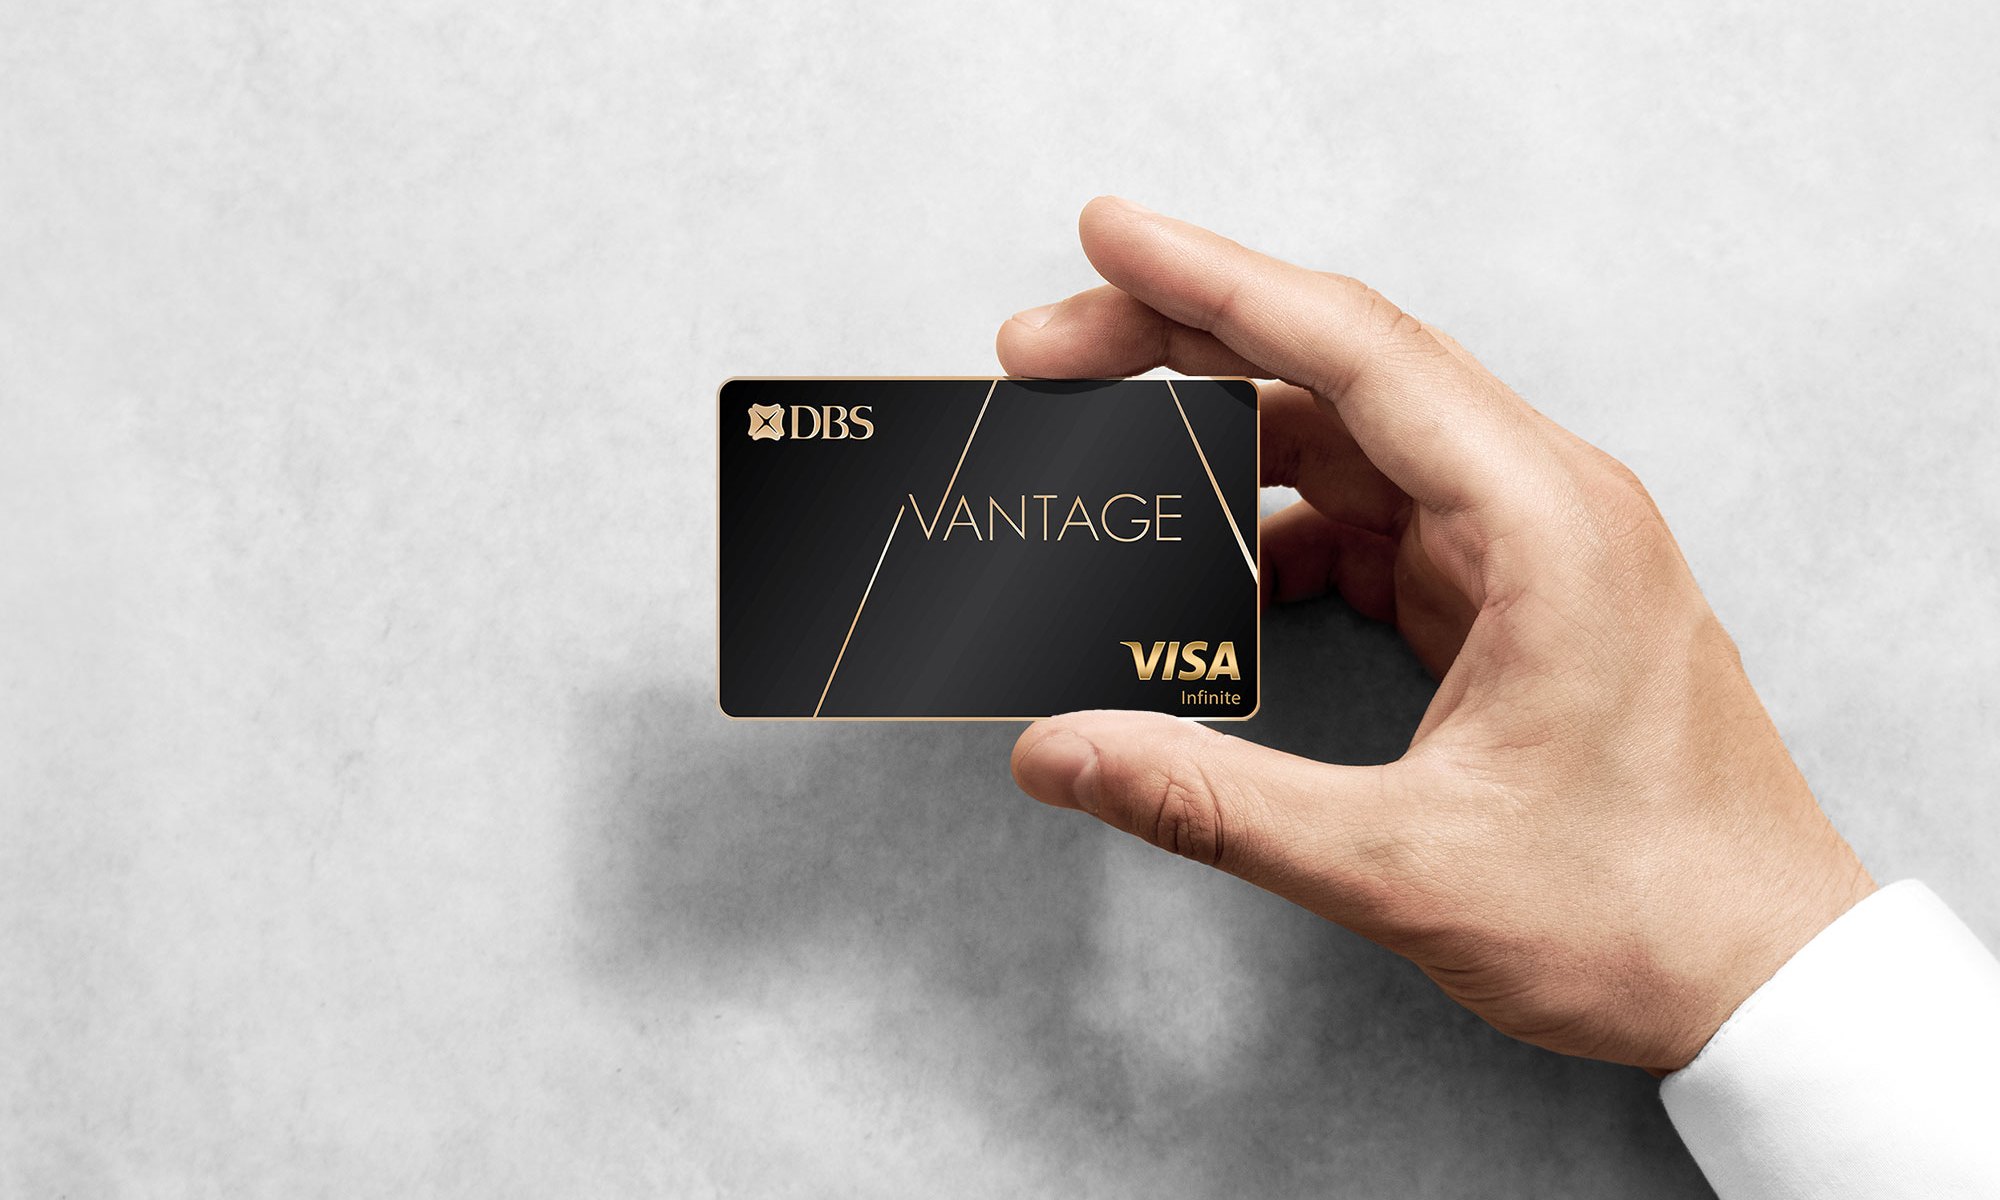

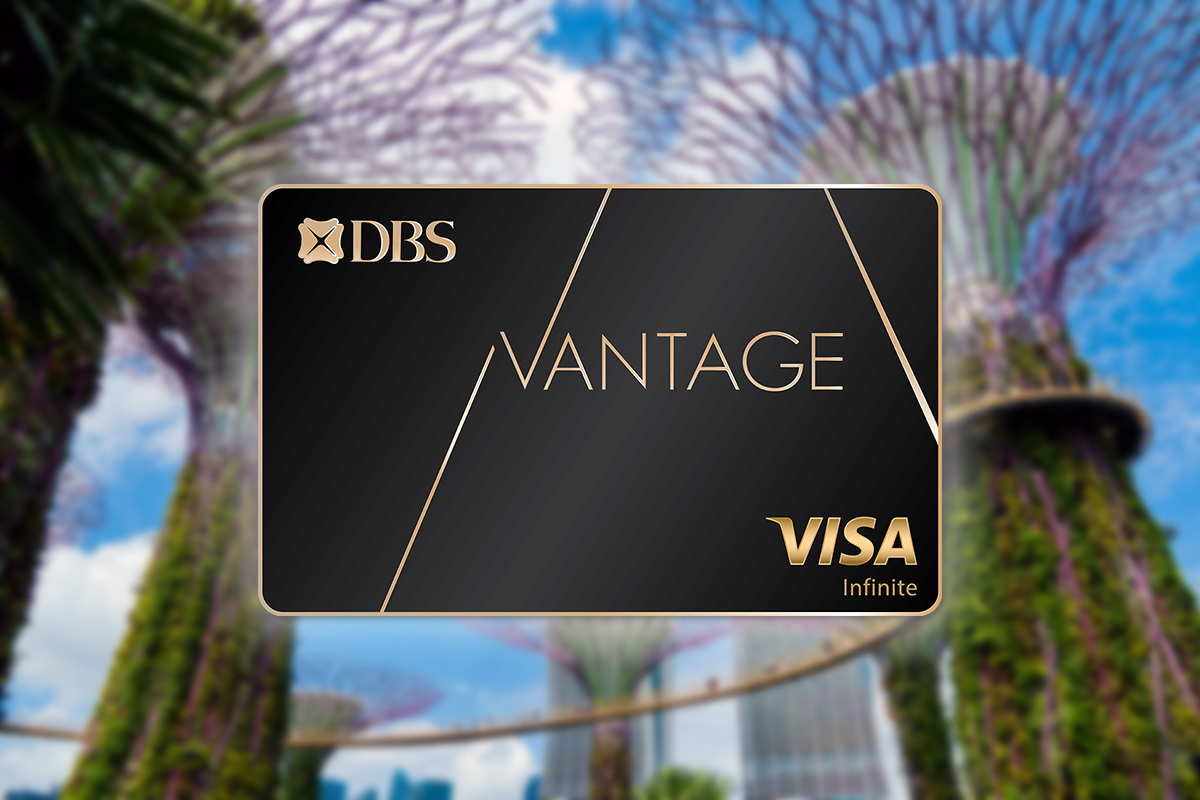
Here’s our review of the DBS Vantage card issued in Singapore. It forms part of our series of credit card reviews, which are all summarised on our dedicated Credit Cards page.
Dollar amounts refer to SGD, and ‘miles’ refer to KrisFlyer miles, except where stated. This review was updated on 14th November 2026.
| DBS Vantage | |||
 |
1.4 mpd on local spend |
10 lounge visits |
2 free hotel nights |
| APPLY HERE | |||
| DBS Vantage | ||
|
||
|
1.4 mpd on local spend |
10 lounge visits |
2 free hotel nights |
| APPLY HERE | ||
Mainly Miles Says
The DBS Vantage Card offers 1.4 mpd on local spend, 2.2 mpd overseas, and 10 annual lounge visits, but it really only shines during one of its generous sign-up bonus campaigns, with up to 85,000 bonus miles offered in the past.
The cuts have been coming thick and fast, though. Since August 2026 DBS has removed the annual fee waiver for those spending S$60,000 or more each year, axed Qantas Frequent Flyer from its transfer partners without telling anyone in advance, then in November trimmed the local earn rate from 1.5 mpd to 1.4 mpd.
The hefty S$600 annual fee can now only be avoided by DBS Treasures clients with Accredited Investor status, and even then you’ll lose the 25,000 renewal miles. Treasures clients do at least get four free airport limo rides.
With no sign-up bonus on offer either, the card is a tough sell right now, and even more so from the second year onwards.
Let’s take a look.
| Pros | Cons |
|
|
Eligibility
- Minimum Age: 21
- Maximum Age: 75
- Minimum Income: S$120,000/yr
The DBS Vantage card has a S$120,000 per year income requirement for all applicants. DBS needs to have a high enough income on file for you – you can update it here if necessary, prior to application.
Annual Fees & Interest Rates
- Annual Fee (principal): S$599.50
- Annual Fee (supplementary): Free
The annual fee for the DBS Vantage card is S$599.50, and for most cardholders it can’t be waived.
Supplementary cards can be added to your account for free.
Until recently the annual fee was waived if you spent more than S$60,000 on retail transactions in your membership year. DBS ended that perk for renewals from 1st August 2026, so you can no longer spend your way to a waiver.
The cut-off was based on your renewal date, not your spend period, so cardholders whose cards renewed before 1st August 2026 got one final waiver. From that date onwards, no amount of spending will trigger it.
Cardholders receive 25,000 bonus miles (12,500 DBS Points) for payment of the annual fee, credited the next working day after the fee is charged.
There is now one way around the fee. Since 2nd November 2026, DBS Treasures clients with Accredited Investor (AI) status can have it reversed, provided they hold at least S$350,000 in assets under management (AUM) with the bank in single-name accounts. AI status must be held individually, so qualifying only through a joint Wealth Management Account doesn’t count.
Don’t expect the fee to simply disappear from your statement, though. DBS bills it as normal and you have to pay it on time, with the money coming back within three months. That clock starts from the date the fee was charged, or from the end of the month in which you qualified if that’s later.
Unfortunately the 12,500 DBS Points (25,000 miles) you get for paying the fee are then taken back, so it’s the fee or the miles, but not both.
The qualifying rules depend on when you got the card and when your annual fee is charged:
- New cardholders: if your card was approved on or after 2nd November 2026, you only need to hit the criteria at one month-end during your first three calendar months, with the month of approval counting as the first.
- Existing cardholders: DBS looks at three month-ends in a row, ending with the month your annual fee is charged. There’s a concession for fees charged up to 31st January 2027, where only that final month-end is checked.
The programme covers annual fees charged between 2nd November 2026 and 31st March 2027. Existing cardholders renewing between 1st April and 1st November 2027 may still be considered, but only at DBS’s discretion. The S$350,000 also has to stay put for the following 12 months. Dip below it and DBS is entitled to bill you the annual fee again. The full conditions are in DBS’s programme terms.
The same clawback applies if the annual fee is waived for any other reason, and if you’ve already transferred the points out, DBS reserves the right to charge you S$0.0388 per DBS Point in cash instead – around S$485 on the full 12,500 – and to recover any shortfall from your other DBS card accounts.
For Treasures clients receiving the fee reversal that’s a risk, since the points are credited the day after the fee is charged but the refund can take up to three months. Make sure you keep at least 12,500 DBS Points in your account until it has gone through.
Other fees and interest rates for the DBS Vantage card include:
- EIR: 27.8%
- Interest-free period: 25 days from statement date
- Minimum payment: 3% (minimum S$50)
- Late payment fee: S$100 (balance more than S$200)
- Cash advance fee: 8% (minimum S$15)
- Overlimit fee: S$40
Sign-up bonus
Both new and existing DBS customers receive 25,000 miles on payment of the annual fee for the DBS Vantage card, however there is no additional welcome bonus as such currently running.
Earning 25,000 miles for a fee of S$599.50 is the equivalent of ‘buying’ miles for 2.4 cents each – which is way more than they are typically worth – but that would assume you place no value on the card’s other perks.
Past sign-up bonuses for the Vantage card have ranged from 60,000 miles (the most recent offer, which was pulled early) to 85,000 miles (which was offered in early 2025), though those totals include the 25,000 miles everyone gets year-round just for paying the annual fee.
Nonetheless the time to acquire the Vantage card is undoubtedly when one of these sign-up bonuses is running, sometimes allowing new-to-bank cardholders to buy miles for as little as 0.71 cents each, before taking account of the card’s other benefits.
Regular earn rates
The DBS Vantage card earns:
- 1.4 mpd for local spend (i.e. transacted in SGD), and
- 2.2 mpd for overseas spend (i.e. transacted in foreign currency).
The local rate was cut from 1.5 mpd on 2nd November 2026, though it still matches the best on offer among Singapore cards in this income category.
Earn rates (S$120k income cards)
(Best to worst, November 2026)
| Card | Local Spend | FCY Spend |
 SCVI |
1.4 mpd* | 3 mpd* |
 UOB VI Metal |
1.4 mpd | 2.4 mpd |
 DBS Vantage |
1.4 mpd | 2.2 mpd |
 OCBC Voyage |
1.3 mpd | 2.2 mpd |
 Citi Prestige |
1.3 mpd | 2 mpd |
 Maybank VI |
1.2 mpd | 3.2 mpd^ |
 HSBC VI |
1 mpd | 2 mpd |
* Subject to a minimum spend of S$2,000 (any currency) in the same statement cycle, otherwise 1 mpd
^ Subject to S$4,000+ spend per calendar month, otherwise 2 mpd
Eligible transactions
DBS has a full list of transactions that will not earn DBS Points (i.e. miles) with its cards. Here are the key ones to watch out for:
- Payments via AXS, SAM, or internet banking bill payments. The former carve-out for AXS Pay + Earn was removed in 2026 – all AXS payments are now excluded.
- Insurance premiums of any kind (life, health, travel, etc.).
- Education payments – schools, universities, and tuition fees.
- Government and tax payments, including IRAS, court fines, and postal / government services.
- Utilities (electricity, gas, water bills).
- Money transfers and funding of accounts, including Wise, Revolut, and brokerage deposits.
- Cryptocurrency purchases or foreign currency wallets.
- Stored value card top-ups – e.g. GrabPay, YouTrip, EZ-Link, ShopeePay, Singtel Dash.
- Betting and gambling transactions (including casinos, lottery, and online wagers).
- Hospital or medical payments (classified under MCC 8062).
- Charity or non-profit donations, including religious organisations.
- Parking – car parks, meters and garages (MCC 7523).
- Tolls and bridge fees (MCC 4784).
- Rent paid directly to a property agent or manager (MCC 6513, added December 2025).
See Section 2.8 of this document for the bank’s full breakdown of excluded transactions.
You can earn miles with the Vantage card for CardUp and ipaymy transactions.
Are KrisFlyer miles credited directly?
No, with this card you’ll actually accrue ‘DBS Points’, for any sign-up bonus and for your spending. These transfer to KrisFlyer miles at a 1:2 ratio, so for S$20,000 of local spending, you’ll net 14,000 DBS Points, worth 28,000 KrisFlyer miles.
When do DBS Points credit?
DBS Points normally show up in your account one to three days after a purchase, as soon as the transaction has posted.
You won’t have to wait until your monthly statement for the points to be added, so if you’re making a purchase to achieve a short-term top-up they should be available to you within a few days.
Which loyalty schemes can I transfer into?
You can transfer DBS Points into Singapore Airlines KrisFlyer and Cathay Pacific Asia Miles. The same earning rate, transfer cost, and minimum transfer ‘blocks’ apply if you choose to credit to Asia Miles. Qantas Frequent Flyer was also an option until DBS dropped it in late September 2026, without any advance notice to cardholders.
| DBS Points Transfer Partners (November 2026) |
|||
| FFP | DBS Points | Miles | |
 |
Singapore Airlines KrisFlyer |
5,000 | 10,000 |
 |
Cathay Pacific Asia Miles |
5,000 | 10,000 |
 |
AirAsia Rewards |
500 | 1,500 |
You can also transfer your DBS Points to AirAsia Rewards points, here 500 DBS Points will transfer into 1,500 points (a 3:1 ratio), though it won’t be much interest to our readers – AirAsia points are worth only about S$0.003 each (0.3 cents), around a sixth of the value of a KrisFlyer mile or an Asia Mile.
Since AirAsia Rewards is effectively a cashback programme, this is even worse value than cashing out your DBS Points for shopping vouchers – and DBS has charged its full S$27.25 conversion fee on these transfers since March 2026, having previously waived it.
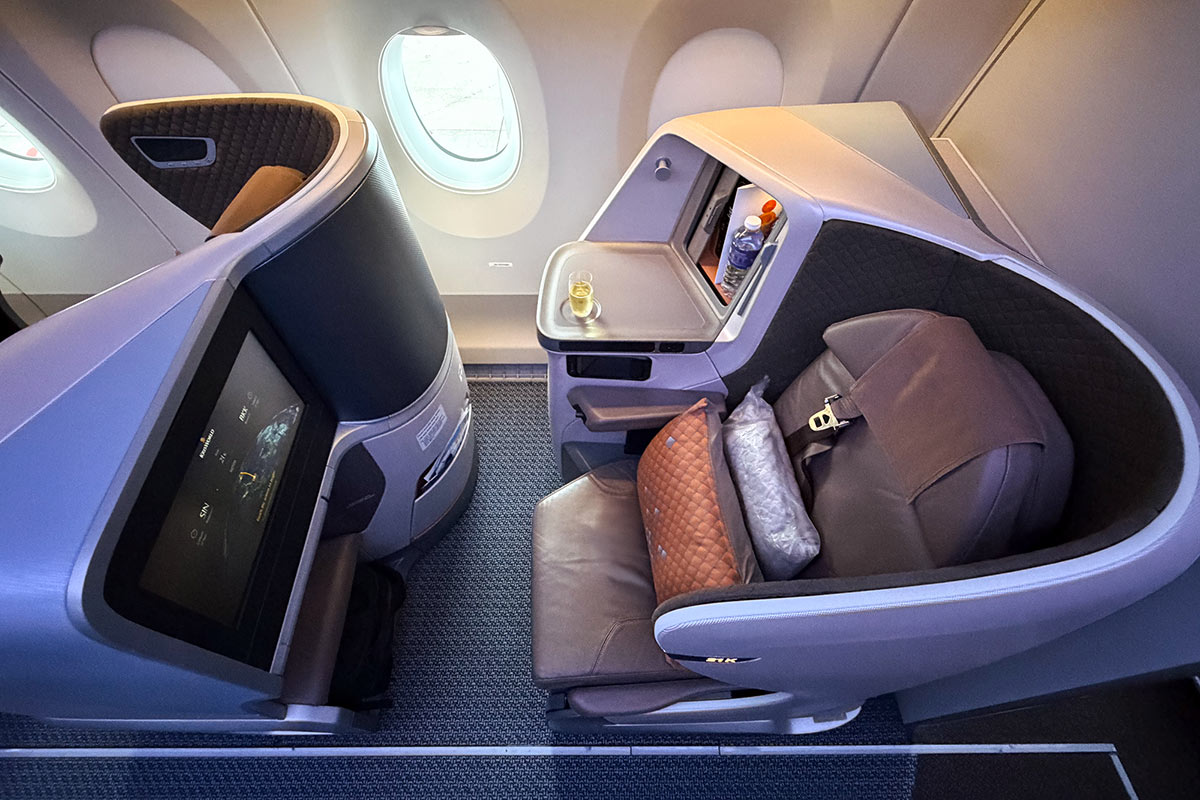
(Photo: MainlyMiles)
↥ Is there a minimum transfer amount?
The minimum volume of miles you can transfer into KrisFlyer is 10,000 (i.e. 5,000 DBS Points). Thereafter they must then be transferred in blocks of 10,000 miles.
The exception is for transfers to AirAsia Rewards, which are at a 500 DBS Points to 1,500 points ratio, so the minimum transfer in that case is 500 Points, with same-sized blocks thereafter, but we really do not recommend a transfer to this programme for the aforementioned reasons.
Instant free transfer to KrisFlyer miles via Kris+
You can also link your DBS Points and KrisPay account and instantly transfer as little as 100 points into KrisPay miles via the Kris+ app.
The transfer ratio is 1:1.7 (e.g. 100 DBS Points = 170 KrisPay miles).
You won’t want to be using the KrisPay miles against Kris+ merchant purchases, due to the poor value of 1 cent per mile, but you can immediately transfer them 1:1 into your KrisFlyer account as KrisFlyer miles.

As you’ll notice the ratio means taking a 15% ‘hit’ on the usual DBS Points to KrisFlyer transfer rate, so it’s only of interest if you need a small amount to meet a specific redemption threshold, or have a small balance ‘stuck’ in DBS Points (less than 5,000), which you aren’t going to be adding to in future.
You shouldn’t be using this as your regular DBS Points to KrisFlyer transfer method, as it effectively devalues your miles earning rate with the Vantage card to 1.19 mpd for general transactions and 1.87 mpd for FCY purchases.
There are important factors to be aware of, firstly you’ll have to move any points transferred from DBS to KrisPay into KrisFlyer miles within 21 days, otherwise they are stuck in KrisPay (where you definitely don’t want them).
The second is just as important, you cannot use any of the KrisPay miles you have earned from your DBS Points transfer for any Kris+ purchase, no matter how small, as that automatically renders the entire transfer stuck in Kris+ until expiry, six months later.
The golden rule therefore is to transfer in to KrisPay miles via Kris+, then transfer straight out to KrisFlyer. Even with that 21-day window available, our advice is don’t wait.
Do DBS Points expire?
Some do and some don’t! The important thing about DBS Points accrued on the Vantage card is that they do expire – after three years.
There’s an issue in year one, though. Points earned in your first year are redeemable only for up to 36 months from the date your card account was opened, not 36 months from when you earned them. So points earned in month eleven effectively get around 25 months, not 36.
From year two onwards the normal rule applies, with points expiring three years after you earn them.
That’s unlike the DBS Altitude card, where points never expire, and represents a big downside for this card.
Once you transfer to KrisFlyer miles, your points will have a further three-year validity. If you transfer into Asia Miles they will never expire, under the scheme’s policy that provided you earn or redeem at least 1 Asia mile every 18 months, your entire balance will remain intact.
This can be achieved by a simple 100 miles carbon offset donation if necessary, or via a card-linked dining transaction in Singapore, assuming you don’t want to transfer more credit card points across.
DBS Points pool between cards
If you have more than one DBS card the DBS Points earned on all your cards will be aggregated for purposes of redemption of rewards, including miles transfers.
DBS Points expiring first will be used first in any redemption transaction.
If you cancel your Vantage Card however, any DBS Points accrued but not redeemed from the card will be forfeited. They cannot be transferred, for example, to your Altitude card.
How long do points take to credit to miles?
Points / miles transfer times are quoted as:
- AirAsia: 5 working days
- Asia Miles: 7 working days
- KrisFlyer: 5 working days
DBS’s rewards terms are looser, allowing up to 14 working days for a first-time transfer to any programme and up to 10 working days after that.
Our personal experience of transferring DBS Points into KrisFlyer miles is that the process takes just one or two days, and our most recent transfer to Asia Miles took just under a week.
What is the transfer cost to miles?
It’s the same for all transfer partners which are part of the programme, S$27.25 each time you transfer DBS Points to airline miles (like KrisFlyer miles).
The exception is the instant free transfer method to KrisFlyer miles via Kris+, but as mentioned this comes at a 15% poorer transfer ratio and so shouldn’t usually be considered, except for small top-ups / orphan points.
Unlike the DBS Altitude card, the DBS Vantage is not eligible for DBS’s auto-conversion programme. That option costs S$43.60 a year and moves your DBS Points across to KrisFlyer once a quarter, 500 points at a time, which is handy for Altitude cardholders who don’t want to bother with manual transfers.
With the Vantage on its own, you’ll need to initiate each transfer manually, paying the S$27.25 fee each time.

There is a way round this if you hold one of the three eligible cards as well – i.e. the DBS Altitude, Insignia or Treasures Black Elite. Enrol with that card and DBS converts the points from all your DBS cards each quarter, your Vantage balance included. DBS’s rewards terms also say you won’t pay the S$27.25 fee on any manual transfers you make while enrolled.
Just remember the automatic conversion sends everything to KrisFlyer, where the miles then have three years before they expire. It happens in the first ten days of January, April, July and October, so if you’d rather send some points to Asia Miles, you’ll need to move those yourself beforehand.
Switch between miles and cashback
The DBS Vantage card offers the option to switch between miles and cashback on a monthly basis.
That means, as an alternative to miles, the card is effectively offering:
- Local Spend: 1.4% cashback instead of 1.4 mpd
- FCY Spend: 2.2% cashback instead of 2.2 mpd
These are inferior rates relative to the value of miles earned, in our opinion, and are unlikely to be of much interest to our readers (unless you value KrisFlyer miles, for example, at less than 1 cent each, in which case there are better cashback cards on the market anyway).
You can switch your earning preference between miles and cashback once per month (assuming you’re changing from the previous month) via the DBS Mobile app.

Your card will be set to earn miles by default when you first receive it.
Beware that if you change your earning preference to cashback, all your DBS Points earned from the Vantage Card will be converted to cashback on the 1st working day of the next calendar month and awarded on the 3rd working day of the next calendar month.
This is not reversible, so be careful! Our advice – don’t mess around with this, stick to miles.
Points rounding
Each transaction you make with the DBS Vantage card, whether in SGD or foreign currency, is divided by 5 and then multiplied by the appropriate number of DBS Points applicable to the transaction.
Only whole DBS Points can be awarded, so there’s a single “round down” at the end, to the next whole point. There’s no intermediate rounding of the dollar amount itself.
For example, assuming a S$57.99 local transaction with the Vantage card:
- S$57.99 / 5 = 11.598 x 3.5 (local spend) = 40.59
- 40.59 rounds down to 40
- 40 DBS Points awarded (equivalent to 80 miles, so you’re getting 1.38 mpd)
Here’s how it works for a S$57.99 foreign currency transaction (after conversion from the relevant FCY amount):
- S$57.99 / 5 = 11.598 x 5.5 (FCY purchase) = 63.79
- 63.79 rounds down to 63
- 63 DBS Points awarded (equivalent to 126 miles, so you’re getting 2.17 mpd)
Note how in both cases the actual earn rates you’re achieving fall a bit short of the ‘advertised’ rates, due to rounding.
↥ Minimum spend to earn points
Since you’ll need to accrue at least 1 DBS Point to earn miles for your transaction (0.99 DBS Points rounds down to zero), the minimum spend in SGD on the DBS Vantage card to earn points is:
- Local transactions: S$1.43
- FCY transactions: S$0.91 (after conversion to SGD)
These are quite reasonable levels, with some credit cards including UOB, Maybank and OCBC products awarding no miles whatsoever for transactions of less than S$5.
FCY fee / cpm overseas
The DBS Vantage card has a 3.25% foreign currency transaction fee, which is now somewhat typical for Singapore credit cards.
With a 2.2 mpd overseas earn rate that gives an effective cost per mile of 1.56 cents, which is mid-table among cards in this income category.
Cost per mile on overseas transactions (S$120k income cards)
(Best to worst, November 2026)
| Card | Fee | Mpd | Cost per mile |
| Maybank VI |
3.25% | 3.2^ | 1.07¢^ |
| SCVI |
3.5% | 3.0* | 1.22¢* |
| UOB VI Metal |
3.25% | 2.4 | 1.43¢ |
| DBS Vantage |
3.25% | 2.2 | 1.56¢ |
| OCBC Voyage |
3.25% | 2.2 | 1.56¢ |
| HSBC VI |
3.25% | 2.0 | 1.71¢ |
| Citi Prestige |
3.25% | 2.0 | 1.71¢ |
* 3 mpd earn rate for the SCVI card is subject to a minimum spend of S$2,000 (any currency) in the same statement cycle
^ 3.2 mpd earn rate for the Maybank VI card is subject to a minimum spend of S$4,000 (any currency) in the same month
Cost per mile also accounts for an additional 0.3% ‘spread’ over money changer currency rates, though this doesn’t apply to all banks and all foreign currencies, so is a worst-case scenario.
If you’re holding a specialised 4 mpd card, like the DBS WWMC, you will of course be able to achieve much better cost per mile for transactions in foreign currency, provided you are spending within the card’s eligible categories and monthly spend cap.
What else can DBS Points be used for?
There are a variety of rewards other than airline miles you can use your DBS Points for, though as usual they all represent much poorer value.
We know that 1 DBS Point can be converted into 2 KrisFlyer miles, which we value at 1.8 cents each, so that’s approximately 3.6 cents value per DBS Point when used this way.
Other transfer options are largely for shopping and retail vouchers, for example a S$10 FairPrice voucher will set you back 690 DBS Points. The same number of points should be getting you 1,380 KrisFlyer miles, worth about S$25. You should never be using your DBS Points for anything other than KrisFlyer miles or Asia Miles transfers.
10 free Priority Pass lounge visits
DBS Vantage principal cardholders receive a complimentary Priority Pass Digital Membership, which offers access to over 1,900 airport lounges and travel experiences worldwide. The membership must be registered online, and is valid for 12 months from the date of activation.

Cardholders receive 10 complimentary visits per membership year, which can be used either for solo entries or those shared with accompanying guests. For example, you could visit a lounge five times with a guest, or ten times alone, or twice as a family of five.
Once all 10 visits have been used, subsequent entries are charged at US$35 per person per visit, automatically billed to your DBS Vantage card. Note that this benefit applies only to the principal cardholder, and cannot be extended to supplementary cardholders.
Priority Pass includes all the usual third-party options at Singapore Changi Airport, and you can search the full lounge list here.

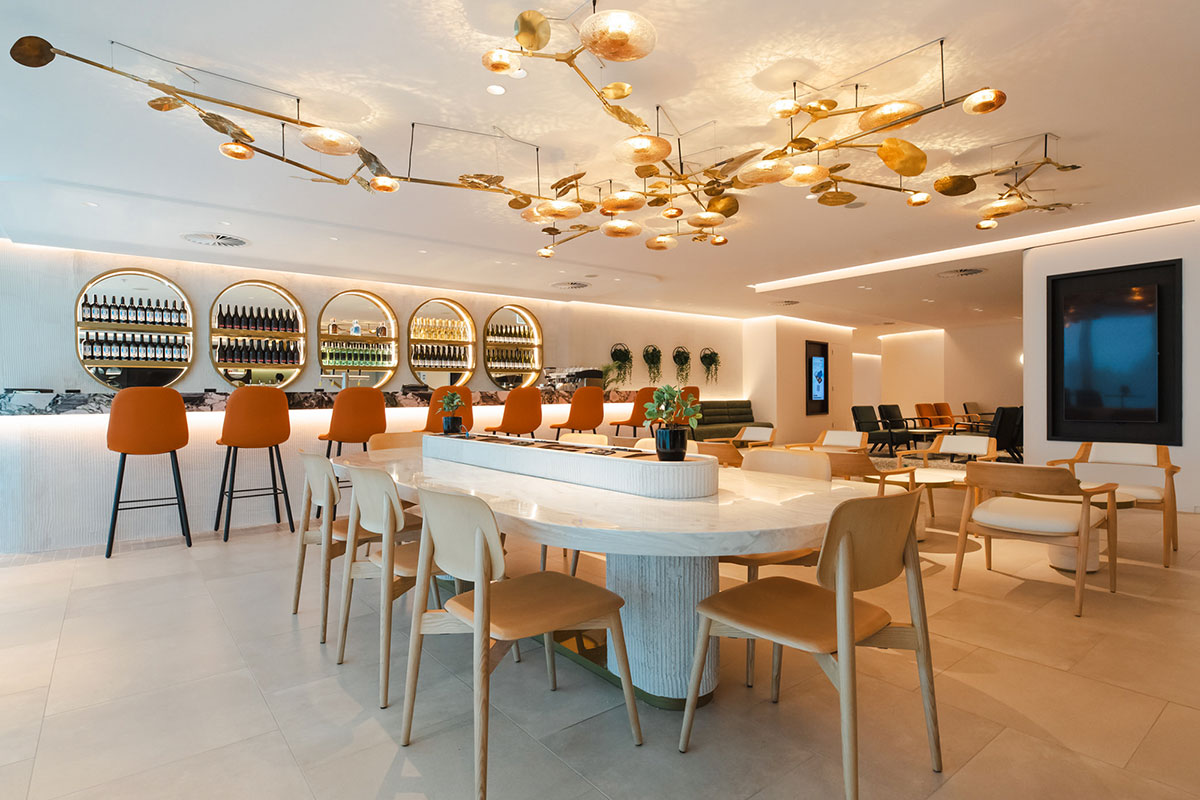
(Photo: MainlyMiles)
While 10 annual visits is a relatively generous allocation, there are a few better options on the market with other Singapore credit cards in this income category, including some unlimited visit allocations. See our recently updated guide for the latest details.

DBS provides an FAQs document about the Priority Pass membership here.
Complimentary ALL Accor+ Explorer membership
DBS Vantage cardholders receive a complimentary ALL Accor+ Explorer membership each year, with benefits at over 1,300 hotels.

However, from 1st October 2025, some key changes came into effect as Accor Plus transitioned to ALL Accor+ Explorer membership, some of them good and some not so good.
Two complimentary hotel nights (with a catch)
The main benefit is two Stay Plus certificates per year (previously one), each redeemable for a complimentary hotel night at participating Accor properties including Sofitel, Pullman, Fairmont, and Swissôtel.
Since 1st October 2025, however, each Stay Plus night now requires a minimum two-night booking, with at least one night paid. The free night will apply to the higher-priced night in the stay.
Previously, no paid night was required.

(Photo: Accor)
That makes it more of a “buy one, get one free” deal, though it’s still decent value if you were going to pay for a two-night stay anyway.
Dining discounts
ALL Accor+ Explorer members get a fixed 30% off food and 15% off drinks at participating Accor hotel restaurants across Asia Pacific, for up to 10 guests.
That replaced the old tiered structure, where two diners got 50% off. Solo diners and bigger groups do better under the new flat rate, but couples lose out.
Hotel discounts and status
ALL Accor+ Explorer members receive:
- 15% off hotel stays year-round (up from 10%), though no longer stackable with member or promotional rates.
- 30 status nights annually (up from 20), granting ALL Gold status, which can get you a room upgrade or a later check-out when the hotel has space.
DBS provides an FAQs document about the ALL Accor+ Explorer membership here.
Free airport limo rides (DBS Treasures only)
Since 2nd November 2026, DBS Vantage principal cardholders who are also DBS Treasures clients can receive four complimentary airport limo rides, something this card has never offered before.
To qualify you’ll need at least S$350,000 in assets under management (AUM) with DBS, held in single-name accounts. There’s no minimum card spend, and unlike the annual fee reversal you don’t need Accredited Investor status.
Here’s how it works:
- The current programme runs from 2nd November 2026 to 31st March 2027. You only need to hit the S$350,000 mark at one month-end in that window to get your four rides, which then last for 12 months. It’s a one-off award, so qualifying again in later months doesn’t add more.
- Within three months of qualifying, DBS emails you a membership number, which you use to set up an account on its limousine partner’s dedicated booking site.
- You must be flying into or out of Singapore and travelling in the car yourself, with rides to or from Changi Airport (Terminals 1 to 4), the JetQuay CIP Terminal or Seletar Airport.
- The vehicle is an MPV for up to four passengers and four bags.
- Bookings must be made at least 48 hours in advance. Cancel less than six hours before pick-up, or fail to show, and the ride counts as used.
Do note that being a Treasures client doesn’t qualify you automatically. The S$350,000 has to actually be there, so anyone holding Treasures status on a smaller balance will miss out.
There’s a longer-term commitment too, as your balance has to remain above that level for a full year after you qualify. Fall short and DBS has the right to withdraw rides you haven’t used yet, and to charge the going rate for any you have. You’ll also lose your remaining rides straight away if you give up Treasures status or cancel the card.
Full details are in DBS’s eligibility terms, limousine service terms and FAQs.
If you don’t bank with DBS Treasures, there are still no limo rides with this card. See our guide to cards with free airport limo rides for the alternatives.
Other benefits
Some of the key additional benefits with the DBS Vantage card which will be of most interest to our readers are:
- Up to 19% instant savings on petrol at Esso stations – 5% Esso station site discount on fuel spend, 5% Esso Smiles Card discount and 9% discount on Synergy Supreme+ (8% on all other Synergy fuel purchases).
- The Culinaire’s List – table reservations and beverage discounts at selected restaurants in Singapore.
- DiningCity membership – offering instant booking confirmations at award-winning restaurants across 16 premier Asian cities, a complimentary welcome drink for all guests, 25% off house drinks and priority access to premium table seating.
- Up to 20% discounts on selected menus at Fullerton Hotel and Fullerton Bay restaurants in Singapore – including Town, Jade, The Courtyard, The Landing Point and La Brasserie.
- GHA DISCOVERY Titanium status as a Visa Infinite cardholder, including benefits like double room upgrade, early check-in.
- Visa’s Luxury Hotel Collection, as a Visa Infinite cardholder. This includes automatic room upgrade where available, complimentary breakfast and a US$25 food and beverage credit.
- Up to 35% discount on Standard car rental rates with Avis President’s Club tier.
- Complimentary weekday golf at Sentosa Golf Club and Tanah Merah Country Club (limited monthly redemptions).
- 50% off weekday green fees at 50 participating golf clubs across Southeast Asia.
Other features
The DBS Vantage card can be used for contactless transactions, and can be added to Apple Pay, Samsung Pay or Google Pay.
The DBS Vantage is a metal card, which some people like for the premium feel. Unfortunately metal cards can be hit-and-miss with contactless payments at some terminals – a slit near the chip acts as an embedded antenna to enable tap functionality, but in practice I certainly find it less reliable than a plastic card in this respect.
If contactless is important to you day-to-day, adding the card to Apple Pay, Google Pay or Samsung Pay and tapping your phone instead is a more reliable option.
Terms and conditions
Here are links to the full terms and conditions applicable to the DBS Vantage card, the DBS Rewards programme and the DBS Treasures Vantage Programme.
DBS Vantage Card T&C
DBS Rewards Programme T&C
DBS Treasures Vantage limo eligibility T&C
DBS Treasures Vantage limo service T&C
DBS Treasures Vantage annual fee reversal T&C
DBS Treasures Vantage Programme FAQs
Our Summary
The DBS Vantage Card offers a competitive local earn rate of 1.4 mpd for general spend, including CardUp and ipaymy transactions, but it’s really only worth picking up when one of the bank’s generous sign-up bonuses is on offer.
That’s not the case at the time of writing, but previous promotions have dangled between 60,000 and 85,000 bonus miles – and we hope to see similar deals make a return soon.
It’s been a year of cuts, too. Since August 2026 there’s no annual fee waiver for those spending over S$60,000 per year, the local earn rate fell from 1.5 mpd to 1.4 mpd in November, and Qantas has disappeared as a transfer partner. That leaves most cardholders with a S$600 annual fee in exchange for 10 lounge visits, 25,000 renewal miles, and two “free” hotel nights (but only if you’re prepared to pay for two more yourself).
DBS Treasures clients get a better deal, with four airport limo rides and a fee waiver if you also have Accredited Investor status, though you’ll give up the 25,000 renewal miles for that.
For most of our readers that’s unlikely to stack up as good value. This is a card to pick up for its first-year sign-up bonus when a strong offer is running, then cancel before the second-year fee.
| Our Rating | ||||||||||||||||||||
| 3 / 5 among high income general spend cards |
||||||||||||||||||||
|
DBS Vantage |
||||||||||||||||||||
How we rate credit cards
|
||||||||||||||||||||
Links on Mainly Miles may pay us an affiliate commission.
(Cover Photo: Shutterstock)